Key takeaways
- Test 1: rental one must still cash flow after the new, larger loan payment, not before it.
- Test 2: rental two must cash flow on its own rent, its own loan and its own costs.
- Test 3: the reserve for both houses is in the bank before the second closing.
- Test 4: you have the hours for two houses, or the management fee is already in tests 1 and 2.
- Loan limits and terms come from the lender; the interest rules come from IRS Publication 527 and your CPA.
Is using equity to buy the next rental a good idea? It can be, but only when four tests pass on your own numbers: rental one still cash flows after the new payment, rental two stands alone, the reserve covers two houses, and you have time for two. For owners of rentals in Fort Worth, Keller and North Richland Hills, the rent figures come from a rental analysis and the loan figures come from your lender, not from guesses.
Below is the four-test table to fill in, a worked example on illustrative numbers, where equity can come from, what IRS Publication 527 says about the interest, and the order of steps. This is general information, not financial, lending or tax advice.
The four tests at a glance: fill them in with your own numbers
Here are the four tests, what to fill in for each, and what a pass and a fail look like:
| Test | Fill in from your own numbers | Passes when | Fails when |
|---|---|---|---|
| 1. Rental one after the new loan | Rent minus the NEW loan payment, tax and insurance escrow, management, a repair reserve and a vacancy allowance | Still positive, or slightly negative with a strong reserve and a strong rental two | Clearly negative: the second purchase now costs you money every month |
| 2. Rental two on its own | Rent from a rental analysis, minus its own loan payment, escrow, management, reserve and vacancy allowance | Positive on real figures | Positive only with an optimistic rent or no reserve |
| 3. A reserve for two | An operating reserve per house, times two, plus a quote for the oldest big system across both houses | Funded in cash before the second closing | Depends on rental two's first months of rent |
| 4. Time for two | Your hours for one house in a year, times two, plus turnovers that may land in different months | You have the hours, or a manager's fee is already in tests 1 and 2 | The plan is to find the time later |
How to read this table: all four must pass. Tests 1 and 2 are added together as one portfolio number; if the combined monthly result is thinner than rental one was on its own, the second house adds work and risk without adding income. Tests 3 and 4 decide whether you survive the first bad month.
A worked example: what a cash-out does to the numbers
Illustrative only, not a quote, a loan offer or market data. Rental one rents for $2,100. A cash-out refinance raises its loan payment from $900 to $1,240 a month. Rental two would rent for $2,050 with its own $1,050 loan payment. Management uses our published Full Service rate of 10% of the monthly rent as the example. Here is each line, per month:
| Monthly line | Rental one today | Rental one after cash-out | Rental two |
|---|---|---|---|
| Rent | $2,100 | $2,100 | $2,050 |
| Loan payment (principal and interest) | -$900 | -$1,240 | -$1,050 |
| Property tax and insurance escrow | -$520 | -$520 | -$480 |
| Management (10% of rent) | -$210 | -$210 | -$205 |
| Repair reserve | -$150 | -$150 | -$150 |
| Vacancy allowance | -$105 | -$105 | -$100 |
| Monthly result | +$215 | -$125 | +$65 |
How to read this table: rental one's costs are $1,885 today and $2,225 after the cash-out (re-added in reverse: $105 + $150 + $210 + $520 + $1,240 = $2,225). The $340 higher payment turns +$215 into -$125. Rental two's costs are $1,985 (re-added: $100 + $150 + $205 + $480 + $1,050 = $1,985), so it clears $65.
Together the two houses make -$125 + $65 = -$60 a month, against +$215 from rental one alone. Over a year that is -$720 instead of +$2,580, a gap of $3,300 ($275 a month times 12). This purchase fails test 1 and the combined test. The fixes are a smaller cash-out, a cheaper second house, or waiting until rental one's rent rises.
Where the equity comes from: the routes, in general terms
Equity is what the rental is worth minus what you owe on it. It grows from your down payment, the principal the rent has paid off and any rise in value. It can leave the property in a few ways; the terms, limits and costs of each come from the lender, so treat this list as questions to ask, not answers:
- Cash-out refinance of the rental. A new, larger loan replaces the old one and you receive the difference. Refinancing a rental property covers the basics.
- A line of credit on the rental, if a lender offers one on an investment property. Ask how the rate and payment can change.
- Equity from your own home. This puts the house you live in behind an investment. For a Texas homestead, the Constitution (article XVI, section 50(a)(6)(B)) limits a home-equity extension of credit so that it, added to all other debt secured by the homestead, does not exceed 80 percent of the homestead's fair market value. Those rules are written for a homestead; a rental that is not your homestead is a different loan, so ask the lender which rules apply.
- Selling rental one and buying with the proceeds. No new debt, but a taxable sale unless deferred; see the 1031 exchange overview and ask your CPA.
Test 1: does rental one still cash flow after the new payment?
Pulling equity out raises the payment on the house that produced it. Run rental one again with the lender's actual new payment and escrow, keeping management, a repair reserve and a vacancy allowance in the costs, and ask: would you buy this house today at these numbers?
In the worked example, a $340 higher payment turns +$215 a month into -$125, a permanent monthly cost of the second purchase whether or not rental two performs. A small negative can be acceptable when rental two clearly covers it and the reserve is strong; a clearly negative one means the equity should stay put for now. How to calculate return on a rental shows the full method.
Test 2: does rental two stand on its own?
Rental two has to carry its own loan, tax, insurance, management, repair reserve and vacancy allowance from its own rent. The equity you put in is not free: its cost sits on rental one's new payment, which is why tests 1 and 2 are added together.
Get the rent from leased comparables, not a listing-site estimate; a rent a couple of hundred dollars too high can flip the combined number. Condition, HOA rules and city requirements are in how to evaluate a rental before you buy.
Test 3: is the reserve for two houses funded before closing?
Two houses mean two HVAC systems, two water heaters, two roofs and two possible vacancies. They rarely fail together, but the reserve has to cover both, and it has to be in the bank before the second closing, not built from rental two's first rents.
Illustrative only: with a policy of $3,000 per house plus a quote of $8,000 for the oldest HVAC system across both, the reserve is $3,000 + $3,000 + $8,000 = $14,000. If the cash-out nets $60,000 and rental two needs $52,000 for the down payment and closing costs, you keep $8,000 ($52,000 + $8,000 = $60,000), which is $6,000 short. The honest fixes are a less expensive second house or a later purchase. How much reserve to keep per rental shows how to size yours.
Test 4: do you have the time for two?
Two leases ending in different months, two sets of showings and two repair lines can double the hours of one self-managed rental. Count your real hours for one house over the last year with the hours log, then decide before the purchase: keep both, hand one off, or hire a manager. A manager's fee belongs in tests 1 and 2; so do your evenings, if you keep the work. How managers quote several homes is in management pricing for multiple rentals, and the growth decisions beyond two houses are in scaling a rental portfolio.
The order of steps: borrow, fund the reserve, then shop
Each step depends on the one before it, and doing them out of order is how purchases fail at closing:
- Ask the lender what rental one can be borrowed against and what the new payment would be, then run test 1.
- Get the equity loan approved, and ideally closed, before you go under contract on rental two. A purchase that depends on a loan that has not closed can fall apart.
- Put the reserve for both houses aside from the proceeds before anything else (test 3).
- Get pre-approved for rental two with the new debt on rental one counted.
- Shop, with a rental analysis on any house you are serious about before the offer (test 2).
The interest on the equity loan: what the IRS publications say
Three points as the IRS states them today:
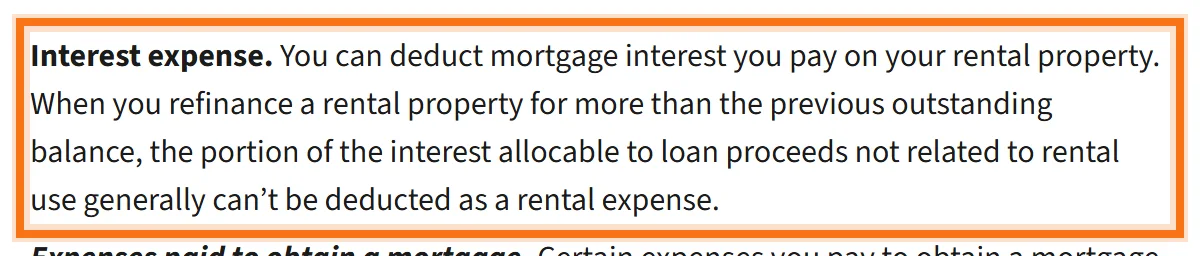
- Refinancing a rental for more than it owed. Publication 527: "You can deduct mortgage interest you pay on your rental property. When you refinance a rental property for more than the previous outstanding balance, the portion of the interest allocable to loan proceeds not related to rental use generally can't be deducted as a rental expense."
- Loan costs. Publication 527 says certain expenses you pay to obtain a mortgage on your rental property, including mortgage commissions, abstract fees and recording fees, can't be deducted as interest; they are capital expenses that are part of your basis.
- A loan on another home. Publication 936 says interest on a mortgage on a home other than your main or second home may be deductible if the proceeds were used for business, investment or other deductible purposes.
How the interest is treated when the cash buys a second rental is a question for your CPA, before you sign. This is general information, not tax advice.
When using equity for the next rental is the right move
It works when rental one still cash flows after the new payment, rental two cash flows on real numbers with its own loan, the reserve for both is funded before closing, the time or the manager is decided, and you plan to hold long enough for loan paydown and value growth to work on two houses instead of one.
If the combined number is thin, waiting a year is a decision too: rental one's rent may rise and the reserve may grow. How a property manager helps you plan more rentals lists what to ask a manager for. Have a lender and a CPA confirm the numbers, and an attorney look at how the houses are titled.
How Perpetual helps before you buy the next rental
Perpetual Property Management is broker-owned, with our office at 5755 Rufe Snow Dr, Suite 155, in North Richland Hills. Justin Brown, a Texas Broker, owns both Perpetual Property Management and our affiliated brokerage, Perpetual Realty Group, LLC. For an owner weighing a second rental, our portfolio page states:
- Start with the rental you own: its statements, lease, maintenance records and upcoming renewal show what ownership actually requires.
- A rental analysis on the prospective purchase: market rent from leased comparables, delivered within one business day, free, whether or not you hire us.
- A review before you commit: a property manager can look at a prospective house before purchase and raise what needs attention or may delay leasing.
- Pricing as you grow: our Investor Special is for portfolios of 5 or more units; with one rental, we review an appropriate plan now and revisit pricing as your holdings change.
We are not a lender or a tax adviser: loan terms come from your lender and the tax treatment from your CPA. Our fees for a second house are confirmed in writing before you sign. To run test 2 on a house you are considering, request a free rental analysis, see every plan on our price sheet, or call 682-593-7033.
The takeaway: Borrow against rental one only when both houses pass on their own after the new payment, the reserve for two is already funded, and the time for two is planned, because leverage repeats a bad year as faithfully as a good one.
Questions owners ask
Is it a good idea to use equity from one rental to buy another?
It can be, if four tests pass on your own numbers: rental one still cash flows after the new loan, rental two cash flows on its own, the reserve covers both houses before closing, and you have the time or a manager for two. It is a poor idea when it leaves both houses thin and the reserve empty, because one bad year then hits twice.
Should I use a cash-out refinance or a HELOC to buy a rental?
Ask the lender for both on the same house: the new payment, how the rate and payment can change, the costs to close and what the loan replaces. Then put each payment into test 1 and see what rental one clears each month. The one that keeps rental one positive with a funded reserve is the stronger choice. This is general information, not lending advice.
How much equity can I take out of a rental property?
The lender sets the limit, so ask before you shop: how much it will lend against the rental, at what payment, after its appraisal. Then run test 1 with that payment. The most a lender will lend is not the amount that keeps both houses healthy; test 3 often says to borrow less.
Should I buy the second rental before or after pulling equity out?
After. Get the equity loan approved and ideally closed first, set aside the reserve for both houses from the proceeds, then get pre-approved for the second purchase with the new debt counted. Going under contract first and rushing the equity loan usually means accepting worse terms.
Can I self-manage two rental properties?
Many owners do, but two houses can double the hours. Decide before the purchase whether you will manage both, hand one off, or hire a manager, and put that cost into the cash flow test either way.
Is the interest on a cash-out refinance of a rental deductible?
IRS Publication 527 says you can deduct mortgage interest you pay on your rental property, but when you refinance a rental for more than the previous outstanding balance, the portion of the interest allocable to loan proceeds not related to rental use generally can't be deducted as a rental expense. Ask your CPA how that applies to your plan; this is not tax advice.
Can I use a home equity loan on my Texas house to buy a rental?
Possibly, but it puts the house you live in behind an investment. For a Texas homestead, the Constitution (article XVI, section 50(a)(6)(B)) limits a home-equity extension of credit, added to other debt secured by the homestead, to 80 percent of the home's fair market value. Ask the lender for the terms and run the four tests before you borrow. This is general information, not lending advice.
Related services
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →