Key takeaways
- Section 1031 applies only to real property held for use in a business or for investment, not to real property held primarily for sale.
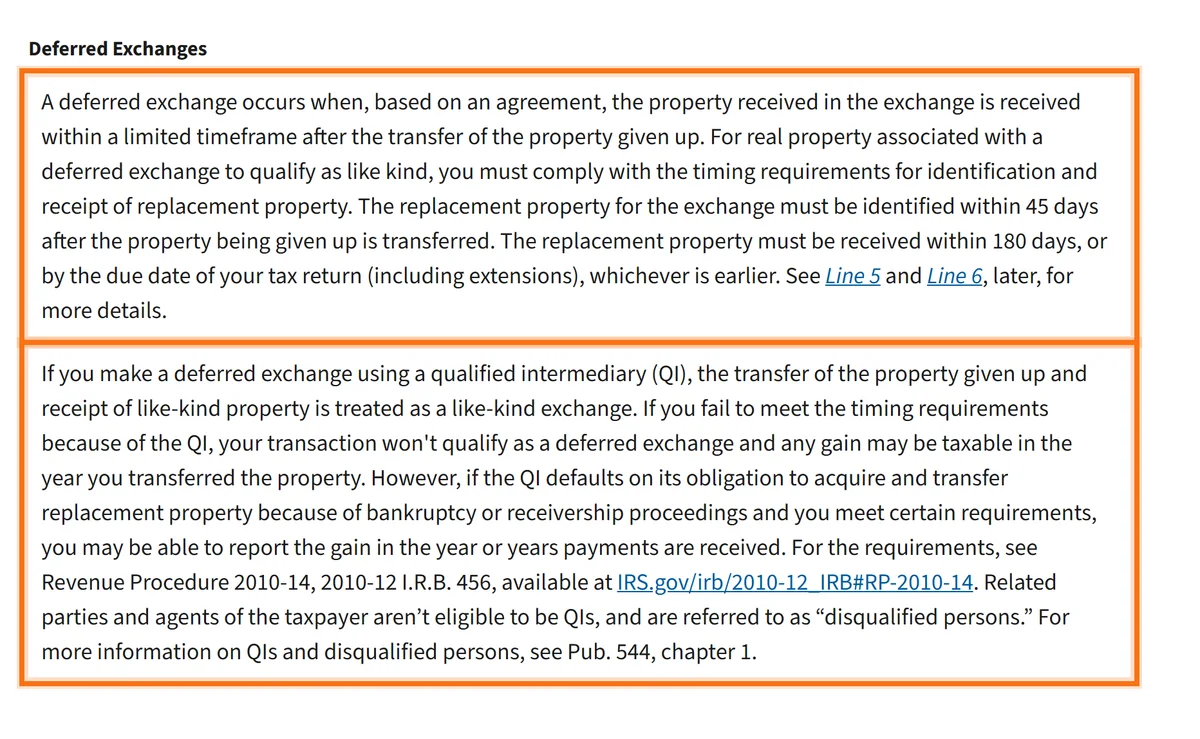
- The IRS deadlines: identify the replacement within 45 days after you transfer the property you sell, and receive it within 180 days or by your return due date (with extensions), whichever is earlier.
- A qualified intermediary holds the sale money; your agent or a related person cannot serve as one.
- Cash or other property you receive is taxed to the extent of the gain, and the deferred gain carries into the new property's basis.
- Texas does not tax individuals' net income (Texas Constitution art. 8, sec. 24-a), so the deferral is federal.
How does a 1031 exchange work in Texas? You sell a rental you held for investment and buy other real property to hold for investment, and the federal tax on the gain waits instead of being paid now. The IRS rules are strict: an intermediary holds the money, the replacement is identified in writing within 45 days and received within 180 days. For an owner in Fort Worth, Keller or North Richland Hills, Texas adds no state income tax, so the rules that matter are federal.
This guide covers what qualifies, the intermediary, the two deadlines, finding the replacement and what to ask your CPA, with the IRS rules quoted from the IRS's own pages. It is general information, not tax or legal advice.
Texas 1031 exchange rules at a glance
Here are the main 1031 exchange rules a Texas rental owner meets, what the IRS says about each, and what it means in practice:
| Rule | What the IRS says | What it means for you |
|---|---|---|
| What qualifies | Real property held for use in a trade or business or for investment; not real property held primarily for sale | A long-held rental qualifies; a quick fix-and-flip generally does not |
| Like-kind | Real properties are generally like-kind, improved or unimproved; U.S. and foreign real property are not | A Keller house can be exchanged for a Fort Worth duplex or land held for investment |
| Identification | Replacement identified in writing within 45 days after the property given up is transferred | Count from the day your sale closes and put the deadline in writing |
| Completion | Replacement received within 180 days, or by the tax return due date (including extensions), whichever is earlier | A sale late in the year can run into the return due date before day 180 |
| Who holds the money | Your agent or a related person cannot be the qualified intermediary | The proceeds go to an independent intermediary, never to you |
| Cash out | Money or other property received is taxed to the extent of the gain | Taking cash out shrinks the deferral |
| Reporting | Report the exchange on Form 8824 | Your CPA files it with the return for the year of the sale |
How to read this table: the first two rows decide whether you can exchange at all, the middle three decide whether you do it correctly, and the last two decide how much tax waits. The IRS column summarizes its like-kind exchange tax tips page and the Form 8824 instructions.
What a 1031 exchange actually does
When you sell a rental for more than your adjusted basis, the gain is normally taxed in the year of sale. The IRS explains that if you make a like-kind exchange, you generally do not recognize a gain or loss under section 1031. The tax is postponed, not forgiven: the gain you did not pay tax on stays with you through a lower tax basis in the replacement property, which Form 8824 figures on line 25.
Part of a gain tied to depreciation you claimed can be treated differently ("recapture"); that is CPA territory, and the basics are in depreciation for Texas landlords.
Texas does not tax individuals' net income: the Texas Constitution, article 8, section 24-a, bars the legislature from imposing one, including on an individual's share of partnership income. For a Texas owner, the exchange is about federal tax. If you buy the replacement in another state, ask your CPA about that state.
What qualifies, and what does not
Since 2018, section 1031 applies only to real property. Both the property you give up and the property you receive must be real property held for use in a trade or business or for investment. The IRS says real properties are generally like-kind whether improved or unimproved, so a single-family rental in Keller exchanged for a duplex in Fort Worth, or for land held for investment, can qualify.
What does not qualify:
- Real property held primarily for sale, such as a house bought to fix and resell quickly.
- Your home. Section 1031 does not apply if the property you give up was used solely as your personal residence at the time of the exchange. A home you lived in and later rented raises separate rules (section 121, covered below).
- Real property outside the United States exchanged for property inside it, or the reverse.
- Personal property, such as equipment, vehicles or furniture, after 2017.
To defer the whole gain, you generally reinvest all the proceeds and replace the debt. Cash or other property you receive is taxed to the extent of the gain, and the Form 8824 instructions count net debt relief, mortgages the other side takes on beyond what you take on, the same way.
Why you cannot touch the money
In a deferred exchange, you sell first and buy later, and the sale money must not reach you in between. Under the IRS's qualified intermediary safe harbor, an intermediary receives the proceeds at the sale closing and sends them to the purchase closing. The Form 8824 instructions are blunt about who cannot do this job: related parties and your agents, called "disqualified persons." Generally, a disqualified person is your agent at the time of the transaction or someone related to you.
The intermediary is engaged before the sale closes, not after. The mistake owners make is selling first, letting the title company wire the proceeds to their own account, and only then asking about an exchange. The order is: decide to exchange, engage the intermediary, add the exchange language to the sale contract, then close with the proceeds going to the intermediary.
Choose the intermediary carefully: ask how the funds are held and kept separate, and ask your CPA or closing attorney for a recommendation. If you miss the deadlines because of the intermediary, the instructions say the transaction does not qualify as a deferred exchange.
The 45-day and 180-day deadlines
Two clocks start on the date you transfer the property you are selling, which for most owners is the sale closing. The IRS states both in the Form 8824 instructions:
- Identification: 45 days. The replacement must be designated in writing, in a document you sign or a written agreement signed by all parties, and described clearly, for example by legal description or street address. No later than 45 days after the transfer, you send it to the person required to transfer the replacement to you or to another person involved in the exchange who is not a disqualified person. If you receive the replacement within the 45 days, the requirement is treated as met.
- Completion: 180 days or the return due date. The replacement must be received by the earlier of the 180th day after the transfer or the due date, including extensions, of your tax return for the year of the sale.
The 45-day window is short for finding, inspecting and contracting on a rental. If you want to name more than one candidate, ask your intermediary how the identification rules apply to you. Owners who do this well are shopping before the first property closes. This is general information, not tax advice.
Finding the replacement property on the clock
The deadline makes the usual buying mistakes more expensive: a rushed purchase that does not cash flow, or a single named property lost to another buyer. What works:
- Ask your intermediary about naming more than one candidate, so a failed inspection does not end the exchange.
- Run every candidate's numbers as you would without the exchange: real rent, property tax, insurance, management and a vacancy allowance. The method is in how to calculate return on a rental property.
- Base the rent on leased comparables, not on an optimistic guess, because the clock does not pause for a second opinion.
An illustrative example, not tax advice. Assume you sell a rental for $400,000 with an adjusted basis of $250,000 and ignore selling costs and debt: the realized gain is $150,000. If you reinvest everything, none of it is taxed now. If you keep $30,000 in cash, the recognized gain is the smaller of the cash and the gain, $30,000, and $120,000 ($150,000 - $30,000) stays deferred.
Selling the rental with a tenant in place
Many exchanged rentals are sold with a tenant in the house, which investor buyers often prefer. The lease and the deposit transfer to the buyer, and Texas Property Code 92.105 makes the new owner liable for returning the deposit from the date it acquires title. What you control is the closing date, because it starts both clocks: you want the sale to close when you are ready to shop.
The details are in selling a rental with a tenant in place, and whether it is time to sell at all is in when to sell a rental property.
Reverse and other exchanges you may hear about
The plain version is sell first, then buy. Two others come up often. In a reverse exchange, the replacement is acquired before the old property is sold, through a qualified exchange accommodation arrangement in which an exchange accommodation titleholder holds title (Revenue Procedure 2000-37, as the Form 8824 instructions describe). In a related-party exchange, special rules apply, including a two-year rule, and an exchange made through a single-member LLC that you or a relative owns counts as one.
Neither is a first-timer's exchange. If one sounds like your situation, a CPA and an intermediary experienced in that structure become essential.
When to call a CPA, and what to ask
Call before you list. Deferral is not always the right answer: an owner leaving rentals, or with a small gain, may be better off paying the tax and being done.
If you once lived in the house, ask about section 121, which the Form 8824 instructions say may let you exclude part or all of the gain when the property was your main home for at least 2 of the 5 years before the exchange.
Questions to bring:
- What is my adjusted basis, and what gain and recapture would a straight sale produce?
- Does my history with this property support investment treatment?
- What value and debt does the replacement need to defer the whole gain?
- Which intermediary do you recommend?
This is general information, not tax, legal or financial advice. A mistake on the money or the dates cannot be fixed afterward, so have a CPA and a qualified intermediary in place before the sale contract is signed.
How Perpetual handles this
Perpetual is not a tax adviser or a qualified intermediary, and we do not tell you whether to exchange: talk to your CPA and your QI. What we can do, as our site states:
- Both sides of the property. Perpetual Realty Group is our affiliated brokerage, led by Broker/Owner Justin Brown, helping investors buy and sell across Dallas-Fort Worth, and managed owners get one team across buying, leasing, managing and selling.
- Selling with a tenant. When you sell a rental, occupied or vacant, we give you the math for both. See selling investment property.
- Rent on the replacement. Our free rental analysis gives a rent range from leased comparables and a written management quote, and you receive it within one business day.
- Managing what you buy. We manage homes in Keller, North Richland Hills, Fort Worth and nearby, with investor portfolios across Tarrant, Dallas, Collin and Denton counties.
To talk through the sale price and the rent on a replacement before your CPA meeting, call 682-593-7033.
The takeaway: A 1031 exchange defers the tax on a rental sale only if the intermediary is in place before closing and the replacement is identified within 45 days and received within 180, so the planning happens before you list, not after you sell.
Questions owners ask
What is a 1031 exchange in simple terms?
It is a way to sell investment real property and buy other investment real property without paying the federal tax on the gain at the time of sale. The tax is deferred through a lower basis in the new property, not eliminated.
Can I do a 1031 exchange on a house I used to live in?
Possibly, if the home has genuinely been held as a rental. Section 1031 does not apply if the property was used solely as your personal residence at the time of the exchange. If you owned and lived in it as your main home for at least 2 of the 5 years before the exchange, section 121 may let you exclude part or all of the gain. That combination is a question for a CPA before you list.
How long do I have to find a replacement property in a 1031 exchange?
The IRS says the replacement must be identified within 45 days after you transfer the property you give up, and received within 180 days or by the due date of your tax return, including extensions, whichever is earlier. Count from the day the sale closes, and start shopping before it does.
Why do I need a qualified intermediary for a 1031 exchange?
Because receiving the sale proceeds yourself breaks a deferred exchange. Under the IRS safe harbor, a qualified intermediary holds the money between the sale and the purchase. Your agent or a related person cannot serve as one, and the intermediary must be engaged before the sale closes, with the exchange language in the sale contract.
Does Texas tax a 1031 exchange?
No. Article 8, section 24-a of the Texas Constitution bars a tax on individuals' net incomes, including an individual's share of partnership income, so for a Texas owner exchanging a Texas rental the deferral is a federal matter. If the replacement is in another state, or you later move, that state's rules may apply, which is another reason to involve a CPA early.
What are the 1031 exchange rules in Texas?
The same federal rules as everywhere: real property held for business or investment, exchanged for like-kind real property, with a qualified intermediary holding the proceeds, the replacement identified in writing within 45 days and received within 180 days or by the return due date. Cash or other property received is taxed to the extent of the gain, and the exchange is reported on Form 8824. Texas adds no state income tax on the gain.
What happens if I take some cash out of a 1031 exchange?
The cash is taxed to the extent of your gain, and the rest of the gain stays deferred. Illustrative only: with a $150,000 gain and $30,000 kept in cash, $30,000 is recognized now and $120,000 is deferred. Debt relief can count the same way, so ask your CPA to run the numbers before you choose a replacement price.
Related services
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →