Key takeaways
- There is no single ROI number for a rental: NOI, cap rate, cash-on-cash and total return each answer a different question.
- Cap rate ignores the mortgage and describes the house. Cash-on-cash (the equity dividend rate) includes it and describes your deal.
- Vacancy is rent you do not receive, not a bill you pay.
- Every input needs a real source: the tax notice, an insurance quote, a written management quote, leased comparables.
How do you calculate ROI on a rental property? Work down from a year of rent: subtract a vacancy allowance and the operating expenses to get net operating income, divide by the price for the cap rate, subtract the mortgage for cash flow, and divide cash flow by the cash you put in for cash-on-cash return. The formulas are the same for a house in Fort Worth, Keller or North Richland Hills; only the inputs change.
Below: each formula, one illustrative example carried through all of them, where each real number comes from in Tarrant County, and three stress tests.
The ROI formulas for a rental property, on one page
Here are the six measures, the formula for each, and the result for the illustrative example used throughout this guide (a $250,000 house, $70,000 of cash invested, $2,200 a month in rent):
| Measure | Formula | Illustrative example | What it answers |
|---|---|---|---|
| Gross yield | Annual scheduled rent / price | $26,400 / $250,000 = 10.6% | Is this house worth a closer look? |
| Net operating income (NOI) | Rent after vacancy allowance, minus operating expenses | $24,200 - $11,101 = $13,099 | What does the property earn before financing? |
| Cap rate | NOI / price | $13,099 / $250,000 = 5.2% | How does this property compare to another one? |
| Cash flow | NOI - annual principal and interest | $13,099 - $12,000 = $1,099 | What reaches your bank account? |
| Cash-on-cash (equity dividend rate) | Annual cash flow / cash invested | $1,099 / $70,000 = 1.6% | What does your own cash earn this year? |
| Total return (ROI) | (Cash flow + loan paydown + value change) / cash invested | ($1,099 + $3,000 + $0) / $70,000 = 5.9% | What did the whole investment do, including equity? |
How to read this table: each line answers a different question, so a house can look strong on one line and weak on the next. The example's cap rate is modest and its cash-on-cash is thin, while total return is higher because the tenant's rent is paying down the loan. The value change is set to zero on purpose: nobody can promise it.
The illustrative example: price, cash invested, rent and expenses
Every number in this example is illustrative only, not a quote, and not a market figure for any Fort Worth, Keller or North Richland Hills neighborhood. Say a house is bought for $250,000 with $62,500 down, plus $7,500 of closing costs and make-ready work, so the cash invested is $70,000. The loan is $187,500, and the example assumes principal and interest of $1,000 a month, or $12,000 a year. Your real payment comes from your loan documents; this guide does not predict rates.
Say it rents for $2,200 a month, or $26,400 a year. The example allows one month of vacancy, $2,200, so the rent actually received is $24,200. The annual operating expenses, again illustrative:
- Property tax: $4,800
- Landlord insurance: $1,600
- Management at 9% of the monthly rent: $2,376 ($26,400 x 9%), counted on all twelve months to stay conservative
- Tenant placement at 75% of one month's rent, $1,650, assumed once every two years: $825 a year
- Maintenance allowance: $1,500
Total operating expenses: $4,800 + $1,600 + $2,376 + $825 + $1,500 = $11,101. The 9% and 75% are the Standard plan on our price sheet, used here only so the example has real formulas behind it.
Gross yield: the quick first filter
Gross yield is annual scheduled rent divided by price: $26,400 / $250,000 = 10.6%. It takes thirty seconds and ignores every cost, so its only job is a first sort, comparing two houses at a glance before you look harder at either.
What it does show is the rent-to-price relationship: a high price with a modest rent means the case rests more on loan paydown and value than on monthly cash. Never buy on gross yield alone.
Net operating income and cap rate
Net operating income is the rent you expect to receive minus every operating expense, before the mortgage. In the example, $24,200 - $11,101 = $13,099. NOI is the property's earning power regardless of how it is financed, which makes it the number to compare across properties and the number a buyer will look at when you sell.
Cap rate is NOI divided by price: $13,099 / $250,000 = 5.2%. It compares one house with another without the financing in the way. A higher cap rate means more income per dollar of price, but it can also reflect an older house or more risk.
Two mistakes inflate NOI: leaving out vacancy because the house is rented today, and leaving out maintenance because nothing has broken yet. Note that vacancy is rent not received, not a bill. IRS Publication 527 makes the same distinction: while a rental is vacant you may be able to deduct ordinary expenses, but you cannot deduct the loss of rental income. What an empty month really costs is in what vacancy really costs.
Cash flow and cash-on-cash return (the equity dividend rate)
Now subtract the mortgage. NOI of $13,099 minus $12,000 of principal and interest leaves $1,099 of cash flow for the year, about $92 a month. That is thin, which is what happens when the price is high relative to the rent.
Cash-on-cash return is cash flow divided by cash invested: $1,099 / $70,000 = 1.6%. You will also see it called the equity dividend rate: the same formula, before-tax cash flow over the equity you put in. It moves sharply when one input changes: a larger down payment, one long vacancy, a rent increase at renewal.
If cash flow is negative, so is cash-on-cash, and the question becomes whether loan paydown justifies feeding the property each month.
Total return: adding loan paydown and value change
Cash flow is not the whole return on a financed rental. During the year, part of each payment reduced the loan principal: say $3,000 in year one, as an illustration. Your loan's amortization schedule gives the real figure.
Total return, sometimes simply called rental ROI, adds that paydown and any change in value to cash flow and divides by cash invested. With value change set to zero: ($1,099 + $3,000) / $70,000 = 5.9%. This guide does not assume an appreciation rate. Instead, note the sensitivity: every $2,500 the value rises or falls moves total return by about 3.6 points ($2,500 / $70,000).
Loan paydown and value change are unrealized: you collect them only at sale or refinance, after selling costs and any tax. Depreciation also changes the after-tax picture: Publication 527 says residential rental buildings are depreciated under GDS over 27.5 years, and land is not depreciated. How that applies to you is a question for your CPA.
Run the example three more times
Three versions to run on your own numbers, each illustrative only and each starting from $1,099 of cash flow:
- A two-month vacancy. You receive $2,200 less rent than the allowance assumed, and a turnover make-ready costs, say, $1,500. Cash flow becomes $1,099 - $2,200 - $1,500 = negative $2,601. The $3,700 swing is more than three years of this example's cash flow.
- A $4,000 air conditioner replacement. The example's maintenance allowance was $1,500, so the extra $2,500 leaves cash flow at $1,099 - $2,500 = negative $1,401. A replacement is a capital item, which is exactly what a reserve is for: see how much reserve to keep per rental.
- A $100 rent increase at renewal. That is $1,200 more rent a year, less 9% management on it ($108), so $1,092 more cash flow, holding the other allowances where they were. On the Standard plan a renewal carries a $200 fee, so that year cash flow is $1,099 + $1,092 - $200 = $1,991, and cash-on-cash rises from 1.6% to about 2.8% ($1,991 / $70,000).
On a single-family rental, vacancy, turnover and big repairs move the return far more than the headline rent.
Where each real number comes from in Tarrant County
Operating expenses are the recurring costs of running the property: tax, insurance, HOA dues, management, leasing fees spread over the tenancy, maintenance, and utilities you pay while it is empty. Not the mortgage (financing) and not capital items like a roof (the reserve). Here is where each real number comes from:
| Input | Illustrative figure | Where the real number comes from |
|---|---|---|
| Property tax | $4,800 | Your Notice of Appraised Value from the Tarrant Appraisal District, and the rates the taxing units for that address set |
| Insurance | $1,600 | A written landlord (dwelling) policy quote for this house |
| Management | $2,376 | The written management agreement; our price sheet lists 7%, 9% or 10% of monthly rent by plan |
| Leasing and renewals | $825 | The agreement; our price sheet lists placement at 50% or 75% of one month's rent and renewals at $149, $200 or $150 by plan |
| Maintenance | $1,500 | The age of the roof, HVAC and water heater, and the property's own repair history |
| Vacancy allowance | $2,200 | Your own turnover history; this guide assumes one month |
| Rent | $26,400 | What comparable homes actually leased for, from a rental analysis |
How to read this table: the middle column is placeholder arithmetic, the right column is your homework. A model built from guesses only looks precise.
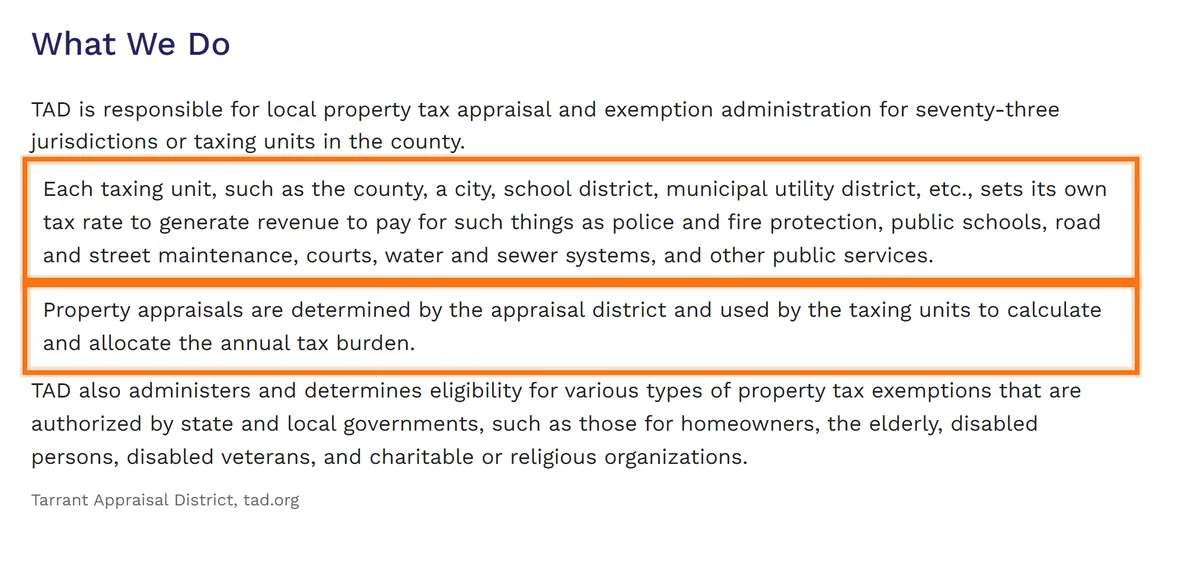
Property tax is the line owners most often guess. The Tarrant Appraisal District appraises the property, and each taxing unit (the county, a city, a school district) sets its own rate. The homestead exemption applies to a residence homestead, so budget a rental from its own notice, not from your home's bill.
Using the ROI formula before you buy
Run every measure on a house before you make an offer, using real inputs: the tax from the appraisal notice and the taxing units, an insurance quote, a management quote in writing, a maintenance allowance based on the age of the major systems, and a rent figure from leased comparables rather than a listing-site estimate. A rent that is $200 a month too optimistic is $2,400 a year that never arrives; even after the smaller management fee on it, the example's $1,099 of cash flow turns negative, and nothing else in the model will warn you.
Then decide which return you are buying: thin cash flow means you rely on loan paydown over a long hold and need a reserve; strong cash flow means you are buying income. Our affiliated brokerage, Perpetual Realty Group, helps investors buy (see buying an investment property), and a free rental analysis gives you the rent line from leased comparables.
Recalculate every year from your statements
The example is a model. After a year your numbers are real: twelve statements with actual rent, actual repairs and actual vacancy days. Rebuild every measure from those once a year, update the value with a broker's opinion rather than an online estimate, and the return stops being a hope and becomes a record. The lines on the statement are explained in how to read your owner statement.
Nothing in this guide is financial, legal or tax advice; a CPA should confirm how depreciation, gains and your own situation affect the after-tax result.
How Perpetual helps with the numbers
We do not run your ROI model for you, and we do not promise a return. What our site states that feeds the model:
- The rent line. A free rental analysis gives a rent range from leased comparables, what similar homes actually rented for, not asking prices, plus a written management quote, whether or not you hire us.
- The management line. Our price sheet lists every fee by plan: 7% (Investor Special, portfolios of 5 or more units), 9% (Standard) or 10% (Full Service) of monthly rent. The final fee is set after the rental analysis, and every number is confirmed in writing before you sign.
- The actuals. Monthly statements in the owner portal, with income, expenses, invoices and documents in one place, are what you rebuild the model from each year.
For the rent and fee lines on your own house, request a free rental analysis or call 682-593-7033.
The takeaway: Compute all of the returns, model vacancy as income you do not receive, take every input from a real source, and rebuild the numbers from your statements each year.
Questions owners ask
What is a good ROI on a rental property?
It depends on the measure and on what you compare it to. A financed single-family rental can show a modest cap rate and thin cash-on-cash with more of its return in loan paydown. Judge the result against your own goals, horizon and alternatives, not a universal target.
What is the difference between cap rate and cash-on-cash return?
Cap rate is net operating income divided by the property price, before any mortgage, and it describes the property. Cash-on-cash is annual cash flow after the mortgage divided by the cash you invested, and it describes your deal. Two buyers of the same house with different down payments get the same cap rate and different cash-on-cash returns.
Should the mortgage be included when calculating rental return?
Not in net operating income or cap rate, which are meant to ignore financing. Yes in cash flow and cash-on-cash, which measure what you actually receive. Total return also credits the principal part of each payment as loan paydown, since the tenant's rent is reducing your loan.
How do I account for vacancy and repairs in a rental ROI calculation?
Include an allowance for both even if the house is rented and nothing is broken. Model vacancy as rent you do not receive (this guide's example uses one month), and set the maintenance allowance from the age of the roof, HVAC and water heater. Keep big replacements separate and fund them from a reserve. Leaving these out produces a return that looks better than any real year will.
Does property management reduce rental ROI?
The fee is an operating expense, so it lowers net operating income on paper: in this guide's illustrative example, 9% of $26,400 is $2,376 a year. Whether the real return falls depends on what management changes in vacancy days, tenant problems and repair costs. Compare a written quote with your own last two years.
How do I work out whether the rent will cover my mortgage, taxes, insurance, and management?
Start from a year of rent based on leased comparables, subtract a vacancy allowance, then subtract property tax, insurance, HOA dues, management, leasing fees and a maintenance allowance. That is net operating income. Subtract a year of mortgage principal and interest; what remains is cash flow. If it is thin, rerun it with a two-month vacancy and a large repair. Perpetual's free rental analysis supplies the rent and a written fee quote.
What is the ROI formula for a rental property?
The simplest version is annual return divided by cash invested. For a rental, the annual return can be cash flow alone (cash-on-cash) or cash flow plus loan paydown plus value change (total return). In this guide's illustrative example, cash-on-cash is $1,099 / $70,000 = 1.6%, and total return with no value change is $4,099 / $70,000 = 5.9%. Always say which one you mean.
What is the equity dividend rate in real estate?
It is another name for cash-on-cash return: annual before-tax cash flow divided by the equity (cash) you invested. In this guide's illustrative example, $1,099 of cash flow on $70,000 invested is an equity dividend rate of about 1.6%. It ignores loan paydown and value change, which total return adds.
Related services
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →