Key takeaways
- Cash flow is cash you can spend this year; appreciation and loan paydown are equity you collect only at a sale or refinance.
- In the illustrative table, a house with $1,800 a year of cash flow ends five years $15,000 ahead of one that needs $100 a month, in every value scenario.
- If the value is flat, the cash-flowing house still makes money and the other one loses it: cash flow is what lets you wait.
- IRS Publication 527: principal payments are not deductible, and depreciation reduces your basis for figuring gain on a later sale.
- Management moves both numbers: vacancy and repairs drive cash flow, and the condition you keep drives the sale price.
Cash flow is what a rental pays you each year after every cost. Appreciation is the change in its value, and loan paydown is the equity the tenant's rent builds; you collect both only when you sell or refinance. For a rental in Fort Worth, Keller or North Richland Hills, weigh them together as total return over the years you will hold it, and keep cash flow positive so you are never forced to sell early.
Below: an illustrative five-year table with three value scenarios, what each return really is, how your time horizon and risk change the weighting, the tax points as the IRS states them, and how management changes each number. No market forecasts: the value changes in the table are hypotheticals.
The five-year total, side by side: an illustrative table
Here are two illustrative houses bought with the same $80,000 of cash and the same loan, held five years, before income tax. House A leaves $1,800 a year after every cost; House B needs $100 a month from you. The value changes are hypotheticals, not a forecast for any DFW market (every number is illustrative only, not a quote):
| Line | House A: positive cash flow | House B: negative cash flow |
|---|---|---|
| Cash flow received over five years | +$9,000 ($1,800 a year) | -$6,000 (you add $100 a month) |
| Loan paydown over five years (from your amortization schedule) | +$22,000 | +$22,000 |
| Selling costs at the end (your agent's net sheet) | -$20,000 | -$20,000 |
| Total if the value is flat | +$11,000 | -$4,000 |
| Total if the value falls $16,000 (hypothetical) | -$5,000 | -$20,000 |
| Total if the value rises $32,000 (hypothetical) | +$43,000 | +$28,000 |
How to read this table: the loan paydown and selling costs are the same for both houses, so the whole difference is cash flow, $15,000 over five years in every row. House A makes money even if the value stays flat; House B needs the value to rise just to come out ahead. Fill the rows in with your own statements, amortization schedule and an agent's net sheet.
The formulas behind a full return calculation, including cap rate and cash-on-cash return, are in how to calculate return on a rental property. This guide is about weighing the parts.
Cash flow: the return you can see on a statement
Cash flow is the rent left after every cost: principal and interest, property tax, insurance, HOA dues, management and leasing fees, repairs, and the months the house sat empty. It is the number you can spend, save or reinvest, and it is the one owners most often overstate, because they subtract the mortgage from the rent and stop there.
Measure cash flow from a year of statements, not from a spreadsheet made before you bought. A statement includes the repair that did not appear in the plan and the weeks between tenants. The month-by-month worksheet for those lines is in will the rent cover the mortgage, taxes, insurance and management.
Its strength is that it is real now. Its weakness is that it is often thin on a single-family house, so one large repair or a long vacancy can erase a year of it. That is why the reserve matters: see how much reserve to keep per rental.
Appreciation and loan paydown: the returns you collect later
Owners tend to blur two different returns under one word:
- Loan paydown: the part of each mortgage payment that reduces principal. The tenant's rent pays it, and it builds equity every month whatever the market does. Your lender's amortization schedule shows the exact figure.
- Market appreciation: the change in value because of the area, demand or improvements. It can be positive, flat or negative, and nobody controls its timing.
Neither one is in your bank account. You collect both only when you sell, refinance or borrow against the equity, and at that moment the value on that date is the only value that matters.
The IRS treats the two sides differently, which is why they feel different on a tax return:
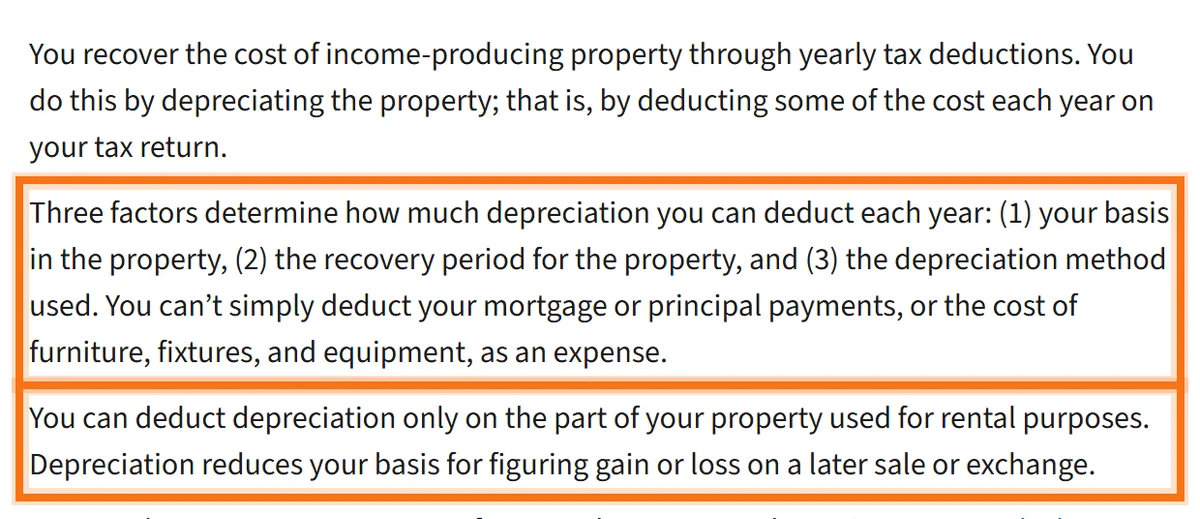
Publication 527 says you cannot simply deduct your mortgage or principal payments as an expense, so loan paydown is a return that never shows up as a deduction. Depreciation does show up as a deduction each year, and the same publication says it reduces your basis for figuring gain or loss on a later sale. More on that below.
Your time horizon decides the weighting
The most useful question is how long you expect to own the house. The answer sorts the weighting:
- A few years. Weight cash flow heavily. Selling costs come out of whatever the value did, and in the table above they take $20,000 before anything else counts. A house that cannot carry itself over a short hold is a bet on the market.
- Five to ten years. Both matter. Thin cash flow is acceptable if the reserve is solid and the house is well kept, and loan paydown starts to add up.
- Ten years or more. Paydown and any value change usually carry the total, and cash flow's job is to keep the house funded through every bad year without you reaching into your pocket.
Trouble starts when the horizon and the weighting do not match: holding a house that needs money every month on a short hold and hoping the value saves it, or selling a house that pays its way because the value moved slowly.
Risk: why cash flow is what lets you wait
Cash flow risk is operational: a vacancy, a tenant who stops paying, a roof, an air conditioner. These turn positive cash flow negative for a season, and they are the risks you can manage with screening, maintenance, inspections and a reserve.
Appreciation risk is market and timing, and you cannot screen the market. What you can control is whether you are forced to sell at a bad moment, and what forces owners to sell is almost always a cash flow problem they could not fund. Cash flow is what lets you wait for appreciation. Look at the falling-value row in the table: House A loses $5,000 and can keep holding; House B loses $20,000 and has been paying in all along.
Leverage multiplies both directions. A mortgage magnifies any value change on your equity and magnifies a bad year too. Before you borrow against one house to buy another, run the tests in using equity to buy the next rental.
How management moves the cash flow line
A management fee is a cost. Whether cash flow ends up lower or higher depends on what the fee replaces in your own results.
The lines management can move: weeks of vacancy between tenants, rent that arrives late or not at all, repairs that grew because they were caught late, and a renewal that slipped until the tenant had already found another house. The lines it adds: the monthly fee, leasing and renewal fees, and maintenance coordination, each listed on a written quote.
The honest test is your own last two years. Count the vacant weeks, the late or missed rent, and the repair bills that grew, then compare them with a fee schedule you can read in full. The comparison is laid out in is property management worth it.
How management moves the value at sale
The value at sale depends on condition, and condition after years of tenants is the product of how the house was run. A home with dated inspection photos, repairs done when they were small and careful move-outs shows and sells better than the same home run until things broke.
Deferred maintenance is appreciation you gave back. A slow leak that rotted a subfloor, drainage that was never corrected, a roof left after storm damage: each one appears either in the buyer's repair request or in the price. Keeping the house in sale condition is the one part of appreciation an owner controls.
Ask any manager how often the inside of the house is inspected, what the report contains, and where the photos are kept. Ours are described on the inspections page.
The tax side, as the IRS publications state it
Taxes change both returns at the end, and they belong to your CPA. What the IRS publications say, as read in November 2026:
- Depreciation each year. Publication 527: you begin to depreciate a rental when you place it in service for the production of income, and residential rental property is depreciated over 27.5 years under the general system. That deduction can make a thin cash flow look better on the return than in the bank.
- Basis at the sale. The same publication: depreciation reduces your basis for figuring gain or loss on a later sale or exchange. The deductions you took raise the gain you report when you sell.
- Rate on that part of the gain. IRS Topic 409: the portion of any unrecaptured section 1250 gain from selling section 1250 real property is taxed at a maximum 25% rate.
On the state side, Texas Constitution article VIII, section 24-b, added November 4, 2025, says the legislature may not impose a tax on the realized or unrealized capital gains of an individual; it does not change property tax. The plain-English version of depreciation is in depreciation for rental owners. This is general information, not tax advice.
Applying it to a house in Fort Worth, Keller or North Richland Hills
Our Keller page notes that many Keller landlords are owners who moved for work and kept the house, and plenty of owners bought for the schools and the location rather than the yield. That is a legitimate reason to own a rental, as long as you know which return you are counting on and the cash flow line does not depend on luck.
Three checks put the table to work on your own house:
- Cash flow from statements: last year's real rent received minus every cost, not the projection.
- Paydown from the lender: the principal portion of the next five years of payments.
- The flat-value row: if the house is worth what it is worth today in five years, does the total still work after selling costs?
If the answer to the third is no and your horizon is short, the decision guide in when to sell a rental property is the next read.
How Perpetual helps you read both returns
We do not forecast values. What we can give you is the operating side of both returns, in writing:
- The rent line: a free rental analysis with a rent range from leased comparables, demand notes and a written management quote, typically within one business day.
- The cost lines: every plan and fee on our pricing page; the final fee is set after the rental analysis, and every number is confirmed in writing before you sign.
- The record behind the value: an annual property inspection on every plan, move-in documentation, photo reports in your owner portal, and documentation on every repair job, with the original vendor invoice in the portal.
- The renewal: renewal work starts 120 days before the lease ends, with the rent checked against leased comparables.
The tax side stays with your CPA. To start with the rent line on a house you own or are buying, call 682-593-7033.
The takeaway: Add the three returns together over your hold, test the total against a flat and a falling value, and keep cash flow positive so the sale happens when you choose it.
Questions owners ask
Is cash flow or appreciation more important for a rental property?
It depends on how long you will hold. Over a short hold, cash flow matters more, because selling costs come out of any value change and the value is unpredictable. Over a long hold, loan paydown and any appreciation usually carry the total, and cash flow's job is to keep the house funded so you are never forced to sell early.
Can a rental be a good investment if it does not cash flow?
It can, if the shortfall is small, your reserve covers it comfortably and your hold is long enough for loan paydown to add up. In the illustrative table, the house that needs $100 a month loses money in the flat and falling value cases, so it depends on the value rising. That makes it a bet on the market rather than a plan.
How does property management affect rental returns?
It moves both. On cash flow: fewer vacant weeks, rent collected consistently, repairs caught early and renewals handled on time can offset the fee, and fees that are unclear can do the opposite. On appreciation: documented inspections and timely repairs preserve the condition that sets the sale price. Deferred maintenance is appreciation given back.
What is loan paydown and does it count as a return?
Loan paydown is the equity you gain as the tenant's rent pays down your mortgage principal. It is a real part of total return and steadier than market appreciation, but you collect it only when you sell or refinance. IRS Publication 527 says you cannot simply deduct principal payments as an expense, so it never shows up as a deduction.
Are single-family rentals in Keller or North Richland Hills better for cash flow or appreciation?
This guide does not rely on market figures for any suburb. The answer for your house comes from three numbers: last year's real cash flow from statements, the principal your lender's schedule shows over your hold, and whether the total still works if the value stays flat. A free rental analysis gives you the rent line from leased comparables.
How does depreciation affect cash flow and appreciation on a rental?
IRS Publication 527 lets you deduct depreciation each year (residential rental property over 27.5 years under the general system), which lowers taxable rental income. The same publication says depreciation reduces your basis for figuring gain on a later sale, and IRS Topic 409 taxes unrecaptured section 1250 gain at a maximum 25% rate. Ask your CPA how it applies to you.
Does Texas tax the gain when I sell a rental?
Texas Constitution article VIII, section 24-b, added November 4, 2025, says the legislature may not impose a tax on the realized or unrealized capital gains of an individual, and section 24-a bars a tax on individuals' net incomes. Federal tax still applies, and property tax is not affected. This is general information, not tax advice.
Related services
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →