Key takeaways
- The worksheet has eight lines: principal and interest, property tax, insurance, HOA, management, the placement fee spread over the lease, maintenance and vacancy.
- Use the tax a rental will pay. A homestead exemption applies to a residence homestead, so your current escrow is usually too low for a rental.
- Tarrant Appraisal District publishes each taxing unit's 2026 rate per $100 of value; your address pays several of them added together.
- Vacancy is rent you do not receive, so subtract it from the rent; do not count it as a bill you pay.
- In the illustrative example below, a $2,300 rent falls $418 a month short; the break-even rent on those costs is about $2,825.
To work out whether the rent will cover your mortgage, taxes, insurance and management, add up eight monthly lines and compare them with the rent you can actually expect after an allowance for vacancy. For a house in Fort Worth, Keller or North Richland Hills, the line owners most often get wrong is property tax: a rental pays without the homestead exemption, at the combined rate of the taxing units for its address.
Below: the worksheet, where each number comes from in Tarrant County, the 2026 tax rates, one illustrative example worked to the dollar, and what to do if the answer is no.
The monthly worksheet for a Tarrant County rental
Here are the eight lines, where the real number for each comes from, and the illustrative figure used in the example later in this guide:
| Line | Where the real number comes from | Illustrative figure |
|---|---|---|
| Expected rent | Leased comparables from a rental analysis, minus the vacancy line below | $2,300 - $192 = $2,108 |
| Principal and interest | Your loan statement (escrow excluded) | $1,350 |
| Property tax | Appraised value from your notice x the combined rate of your taxing units / 12 | $552 |
| Landlord insurance | A written quote for a dwelling (landlord) policy / 12 | $150 |
| HOA dues | The association's statement, including any master association | $45 |
| Management fee | The written management agreement | $207 (9%) |
| Tenant placement fee, spread | The fee in the agreement / expected months per tenant | $72 |
| Maintenance allowance | The age of the roof, HVAC and water heater, and repair history | $150 |
| Vacancy allowance | Rent x months you expect empty per year / 12 | $192 (taken off the rent) |
How to read this table: the rent line is the only one that comes from the market, and it is the one to be most careful with. Every cost line comes from a document you can hold. If a line in your own worksheet is a guess, mark it, because a worksheet with three guesses in it is only a hope.
Start with the rent you can actually get
Every cost line is knowable. The rent is the line you can get wrong, usually by using asking rents from listings or an online estimate. The number to use is what comparable houses nearby, with similar size, age and condition, actually leased for. A free rental analysis gives that as a range; what a rental analysis should include explains how to judge one.
Use the middle of the range, then subtract a vacancy allowance: the rent you do not receive while the house is between tenants. One month a year, $2,300 / 12 = $192 a month, is the assumption this guide's example uses; a house you expect to turn over more often needs more. If the house only covers at the top of the range with no vacancy, it does not cover.
The property tax line: 2026 rates in Keller, NRH and Fort Worth
The Tarrant Appraisal District sets the value; each taxing unit (a city, the county, the hospital district, the college district, a school district and sometimes a special district) sets its own rate. Your bill is the value times the sum of the rates of the units for your address. TAD's 2026 schedule, last updated October 22, 2026, lists these rates per $100 of value:
| Taxing unit | 2026 rate per $100 | Type of unit |
|---|---|---|
| City of Keller | 0.300417 | City |
| City of North Richland Hills | 0.555144 | City |
| City of Fort Worth | 0.70565 | City |
| Tarrant County | 0.186 | County |
| Tarrant County Hospital | 0.159 | Hospital district |
| Tarrant County College | 0.12 | College district |
| Birdville ISD / Keller ISD / Fort Worth ISD | 1.18654 / 1.0852 / 1.029099 | School districts |
How to read this table: add the rates of the units listed for your address on your own notice or tax statement. The list here is only the units this guide uses; the TAD schedule has more, such as municipal utility districts, and an address can pay a unit not shown here.
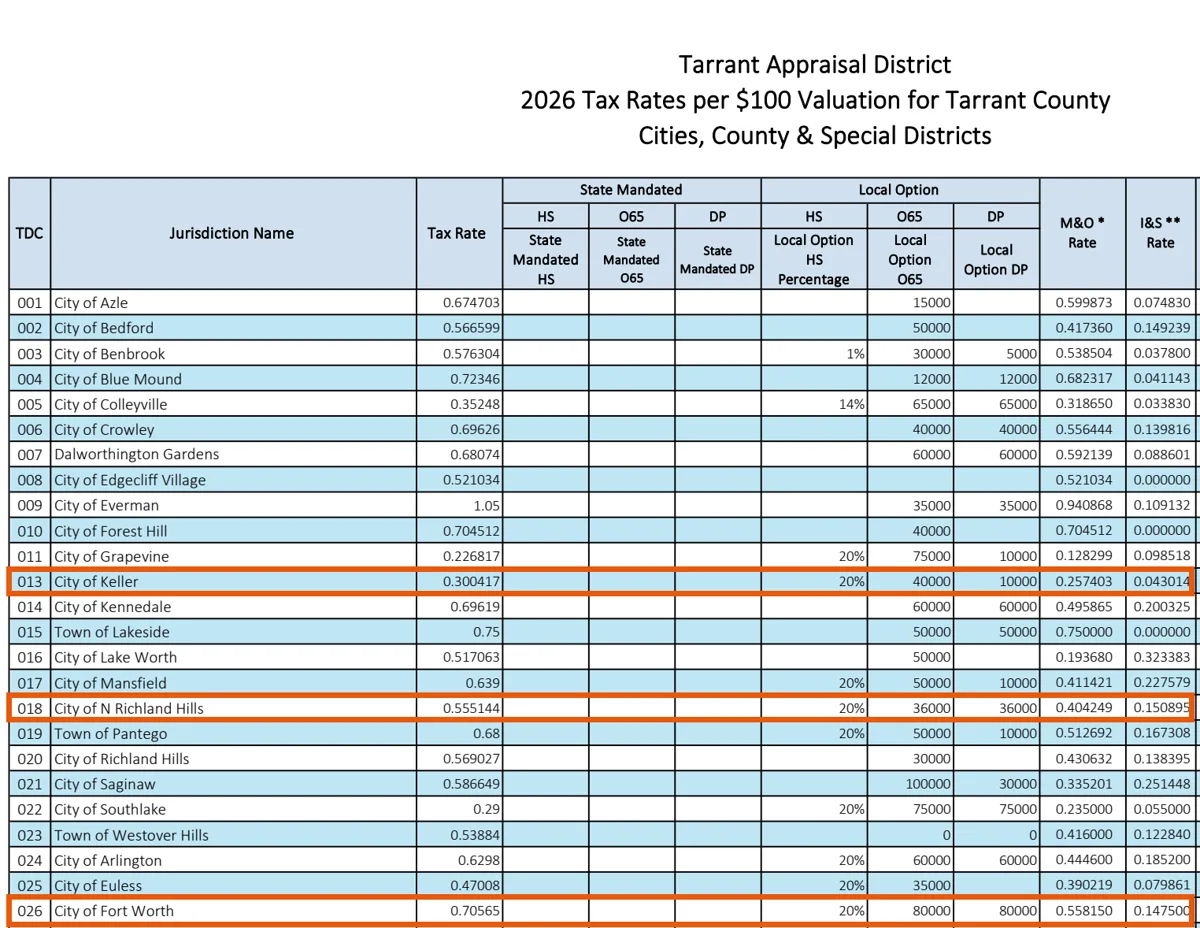
For an address taxed by exactly NRH, Tarrant County, the hospital district, the college district and Birdville ISD, the combined 2026 rate is 0.555144 + 0.186 + 0.159 + 0.12 + 1.18654 = 2.206684 per $100. On an illustrative $300,000 value with no exemption: $3,000 x 2.206684 = $6,620.05 a year, or $551.67 a month. Illustrative only, not a quote; your notice and your units decide the real figure. More on how rentals are taxed is in rental property taxes in Texas.
Why your current escrow is the wrong number
Your mortgage payment probably includes escrow for taxes and insurance, and both numbers are set for the house as your home. A rental is different on both:
- Tax. The homestead exemption is for a residence homestead. In the 2026 TAD schedule, the school districts above show a $140,000 state-mandated homestead exemption and NRH, the county and the hospital district a 20% local option. Separately, Tax Code 23.23(c) says the homestead appraisal cap "expires on January 1 of the first tax year" that neither the owner nor the owner's spouse or surviving spouse qualifies for the exemption. When that happens is covered in the homestead exemption when you rent your home.
- Insurance. A homeowners policy is written for the person living in the house. Texas OPIC describes dwelling insurance as usually covering the house and other structures, and notes it "does not pay for someone else's injuries and the damage to their property." Get a landlord quote and ask how liability is covered; see landlord vs homeowners insurance.
Illustrative only: the same $300,000 NRH house above with the homestead exemptions in that schedule (and ignoring the cap and any other exemption) would owe about $4,415 a year, $368 a month. As a rental, $552. The escrow understates the rental's tax by about $184 a month. This is general information, not tax or insurance advice.
An illustrative example, worked to the dollar
Illustrative only, not a quote. Assume the NRH house above leases for $2,300, with one month of vacancy a year. Principal and interest is $1,350, tax $552 (from the 2026 rates), a landlord policy quote of $1,800 a year ($150), HOA dues of $45 and a maintenance allowance of $150. For the management lines, the example uses the Standard plan on our price sheet, only so the numbers have a real formula: 9% of monthly rent ($207, counted on the full rent to stay conservative) and tenant placement at 75% of one month's rent, $1,725, spread over a 24-month tenancy ($72). Here is the month, line by line:
| Line | Monthly |
|---|---|
| Rent | $2,300 |
| Less vacancy allowance (one month a year) | -$192 |
| Expected rent | $2,108 |
| Principal and interest + tax + insurance + HOA | $1,350 + $552 + $150 + $45 = $2,097 |
| Management + placement spread + maintenance | $207 + $72 + $150 = $429 |
| Total costs | $2,526 |
| Expected rent minus costs | -$418 a month (-$5,016 a year) |
How to read this table: on these assumptions the house does not cover, by $418 a month, before any large repair. With a $950 principal and interest payment instead, costs fall to $2,126 and the gap is $18 a month, which is break-even, not cover. Working backward, these costs break even at a rent of about $2,825: $2,247 of fixed costs divided by the share of rent left after vacancy, management and placement (1 - 0.2046 = 0.7954).
Three mistakes that make the rent look like it covers
The first is using the escrow numbers, which reflect a homestead exemption and a homeowners policy. The second is counting twelve months of rent and no vacancy, when every lease ends. The third is leaving out the placement fee and the turnover work because they are not monthly, when they come back with every new tenant.
Fix all three and a house that looked like it cleared by a few hundred dollars may not clear at all. That is the honest number, and it is better to meet it on paper than in your bank account.
What "covers" means, and what it does not
Rent covering costs means the house does not need money from you each month. It does not mean the house is a good investment, and a small shortfall is not automatically a bad one: part of each payment reduces the loan, and the tax treatment of a rental differs from a home. Those returns never appear in the monthly check.
This worksheet answers one question, cash in versus cash out each month. The full return, with cap rate, cash-on-cash and loan paydown, is in how to calculate return on a rental property. Whether a shortfall is acceptable for you is a question for you and your own advisers; this guide is not financial or tax advice.
If the rent does not cover
Check each line before deciding anything:
- Rent: it only moves if the leased comparables support it; pricing above them buys vacancy, not income.
- Tax: if the appraised value looks high, the Tarrant Appraisal District website lets owners provide evidence and file a protest online.
- Insurance: compare written quotes and read the deductibles.
- Management: read which fees are monthly and which are triggered by an event, such as placement or renewal.
- Reserve: if you will carry a shortfall, know how many months you can carry it; see how much reserve to keep per rental.
What an empty month really costs, beyond the rent itself, is in what vacancy really costs.
How Perpetual helps with the worksheet
Our rent-or-sell page puts the test plainly: leasing fits when the rent covers the mortgage, taxes and insurance with room to spare. What our site states that feeds the worksheet:
- The rent line. Our free rental analysis gives a rent range from leased comparables, what similar homes actually rented for, factoring in condition, features, school zones and demand, plus a written management quote, whether or not you hire us.
- The management lines. Our price sheet lists every fee by plan: 7% (Investor Special, portfolios of 5 or more units), 9% (Standard) or 10% (Full Service) of monthly rent; tenant placement at 50%, 75% or 50% of one month's rent; renewal at $149, $200 or $150. The final fee is set after the rental analysis, and if a fee is not in the agreement, you do not pay it.
- The actuals. Monthly statements and the Owner Portal, with income, expenses and documents in one place, are what you check the worksheet against once the house is rented.
Whether the management fee is charged in a month the house is empty, and how your plan applies to your house, are confirmed in writing before you sign. For the rent and fee lines on your house, request a free rental analysis or call 682-593-7033.
The takeaway: Fill in all eight lines from real documents: the loan statement, the appraisal notice and your taxing units' rates, an insurance quote, the HOA, a written management quote. Subtract vacancy from the rent, not from your bank account, and compare. If it only covers at the top of the rent range, it does not cover.
Questions owners ask
What percentage of rent should I budget for maintenance on a rental house?
There is no single right figure. It depends on the age and condition of the roof, HVAC, water heater and plumbing more than on the rent. Set a monthly allowance from the systems you actually have and keep a separate reserve for big replacements, rather than hoping the allowance builds up in time. The illustrative example in this guide uses $150 a month as a placeholder, not a recommendation.
Do I include the leasing fee when working out whether rent covers my costs?
Yes. It is not monthly, but it comes back every time a tenant changes. Divide the fee in your agreement by the number of months you expect a tenant to stay and carry that as a monthly line. In this guide's illustrative example, a placement fee of 75% of a $2,300 rent is $1,725, which over 24 months is about $72 a month.
Should I use my current escrow payment for taxes and insurance?
No. The escrow reflects a homestead exemption and a homeowners policy, so budget the rental without either. Recalculate the tax from the appraised value with no homestead exemption times your taxing units' combined rate, and get a landlord policy quote. In this guide's illustrative NRH example, the escrow understates the rental's tax by about $184 a month.
Is it worth renting out a house that only breaks even?
That depends on things only you can weigh: your reserve, how long you plan to hold, your loan and what else you could do with the money. The monthly check does not show loan paydown or tax effects, so break-even is not the same as losing money. But if one repair would leave you unable to pay, break-even is a risk. This is general information, not financial advice.
What are the 2026 property tax rates in Keller, North Richland Hills and Fort Worth?
Tarrant Appraisal District's 2026 schedule lists, per $100 of value: City of Keller 0.300417, City of North Richland Hills 0.555144 and City of Fort Worth 0.70565; Tarrant County 0.186, Tarrant County Hospital 0.159 and Tarrant County College 0.12; and Birdville ISD 1.18654, Keller ISD 1.0852 and Fort Worth ISD 1.029099. Your own notice or tax statement lists which units tax your address.
How do I calculate property tax on a rental in Tarrant County?
Take the appraised value on your notice, divide by 100, and multiply by the sum of the rates of every taxing unit for the address, with no homestead exemption. Divide by 12 for the monthly line. In this guide's illustrative example, a $300,000 house in NRH and Birdville ISD at a combined 2.206684 owes $6,620.05 a year, or $551.67 a month.
Related services
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →