Key takeaways
- Know your reason first: a lower rate or different term, cash out, or a change of loan type. Each is judged by what it does to the rental's monthly cash flow.
- Lenders set their own terms for investment property. Get the rate, fees, points, reserve rules and how rental income counts in writing before you apply.
- The rental side of the file is the signed lease, proof the rent is paid, the insurance and your monthly statements.
- The tenant's permission is not needed, but access for the appraiser is set by the lease's access clause. Texas has no statute that sets an entry notice period.
- IRS Publication 527: points on a rental loan are generally deducted over the life of the loan, not in the year you pay them.
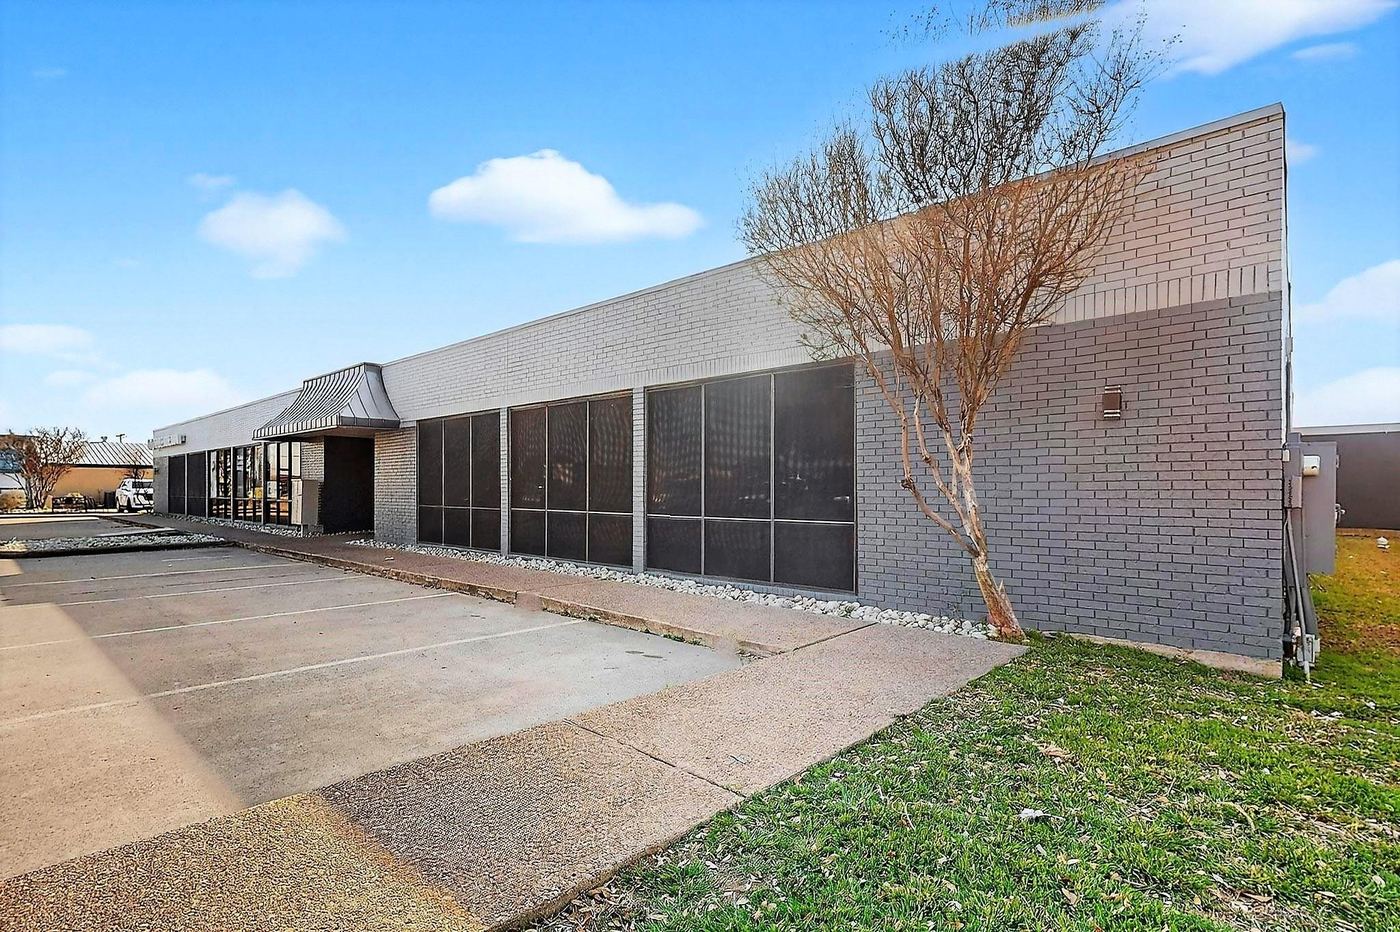
Refinancing a rental property means replacing the loan on a home you rent out, for a better rate or term, to take cash out, or to change the type of loan. The lender decides on paper, so the work is mostly documents: the lease, the rent record, the insurance and the appraisal. On a rental in Fort Worth, Keller or North Richland Hills with a tenant in place, the appraisal visit is the step that needs the most care.
This guide covers the steps, what to ask a lender, the papers, the appraisal with a tenant at home, timing around the lease, the tax rules on points, and the numbers to run. It is not a recommendation to refinance.
A rental refinance, step by step
Here is the order a refinance on a rented house usually runs in, what the rental has to supply at each step, and who handles it:
| Step | What happens | What the rental supplies | Who handles it |
|---|---|---|---|
| 1. Decide the goal | Rate and term, cash out, or a change of loan type | Twelve months of real income and expenses | You, with your CPA |
| 2. Get terms in writing | Rate, fees, points, reserves, how rental income counts | The current rent and the lease end date | The lender |
| 3. Gather the papers | Application, income, assets, credit | Signed lease, rent record, insurance, statements | You, from the owner portal |
| 4. Appraisal | An appraiser walks the inside of the home | Access under the lease, a tidy home | Your manager and the tenant |
| 5. Closing | New loan, new payment date, escrow set up | Insurance updated with the new lender | You and the lender |
| 6. After closing | Records for the tax return | Closing statement, Form 1098s, how cash-out money was used | You and your CPA |
How to read this table: steps 1 and 2 decide whether a refinance makes sense at all, before any fee is paid. Steps 3 and 4 are where a rental differs from a home you live in, and where a managed property usually has its papers ready.
The three reasons owners refinance a rental
Know which of the three reasons is yours before calling a lender, because the loan products differ.
- Rate and term. Replacing the loan with one that has a better rate, a different term or a different structure, without taking cash out. The goal is a lower payment or a faster payoff.
- Cash out. Borrowing against the equity and receiving the difference, often to buy another property or fund major improvements. The balance and the payment go up, so the rental's cash flow has to carry it. The purchase side is in using equity to buy your next rental.
- Changing the loan. Moving a home you used to live in onto an investment loan, moving from an adjustable rate to a fixed one, or removing a co-borrower after a life change.
Then ask each lender, in writing: the rate, fees and points, the cash reserves it requires after closing, how much of the rent it counts and what proves it, and any waiting period before a cash-out. Those answers decide whether a refinance is possible before the rate ever matters.
The paperwork a lender may ask for on a rental
Beyond the usual income, asset and credit documents, a refinance on a rental adds papers about the property itself. Ask each lender for its list. Items a lender may ask for on a rental:
- The current signed lease and its addenda, showing the rent, the term and the tenant.
- Proof the rent is paid: bank deposits or the manager's statements.
- Tax returns showing the property on Schedule E, if you have owned it through a tax year.
- The insurance policy on the property, and any HOA information and the current tax bill.
- The management agreement and a run of owner statements.
This is where a managed property has a quiet advantage. A year of monthly statements showing rent, expenses and disbursements is the record a lender is asking about, and it is already in the owner portal. What each line on a statement shows is in how to read your owner statement.
Refinancing with a tenant in place: the appraisal visit
Do you need your tenant's permission to refinance? No; the loan is between you and the lender. What you need is access for the appraiser, and that is set by the lease, not by a Texas statute: no Texas statute sets a notice period for a landlord to enter a rental house. Read the access clause and give the notice it requires. Landlord entry rights in Texas covers the clause.
What makes the visit go smoothly:
- Tell the tenant in writing, well ahead, what is happening, who is coming and roughly how long it takes.
- Offer a window and let the tenant choose a time within it.
- Ask, without demanding, for the home to be tidy and pets secured, and say plainly that the refinance does not change their lease.
Ask the lender whether the appraisal will include an opinion of market rent. If your rent is below market because you kept a long-term tenant at a modest rate, you want to know how the lender treats the gap before the report arrives.
Timing the refinance around the lease
The easiest time to refinance a rental is mid-lease with a tenant who pays on time: the lease has term left and the rent history is clean. The hardest is during a vacancy, when there is no lease to show and the rent is a projection.
If the lease ends soon, settle the renewal before you apply; a renewed lease with a fresh term is a stronger document than one with weeks left. If the tenant is leaving, it is often simpler to re-lease first and apply once the new tenant has paid, unless the lender accepts a signed lease and deposit. Our renewal process starts 120 days before the lease ends, which leaves room to plan either way. Then set the new payment date so it lands after rent arrives, not before.
The numbers to run before you apply
Two calculations decide most refinances. The numbers below are made up to show the method. Illustrative only, not a quote:
| Question | Assumptions | Arithmetic | Result |
|---|---|---|---|
| Rate and term: when do the costs pay back? | Costs to refinance $5,000; payment drops $150 a month | $5,000 / $150 | About 33 months (33.3) |
| Cash out: does the house still pay for itself? | House nets $300 a month today; cash-out adds $400 to the payment | $300 - $400 | The house now needs $100 a month from you |
How to read this table: the first row says a rate-and-term refinance only pays if you will keep this loan longer than the payback period. The second says a cash-out has to earn more than it costs the first house, here more than $100 a month, and your reserve has to carry the gap meanwhile. Run both with real quotes, including the new escrow for tax and insurance. A refinance that improves the rate but breaks the cash flow is not an improvement. The full method is in how to calculate return on a rental property.
How the IRS treats points and refinancing costs on a rental
The tax side of a refinance follows IRS Publication 527, Residential Rental Property. Four rules from it are worth knowing before you sign a closing statement:
- Points are spread out. Points are prepaid interest, so you generally can't deduct the full amount in the year paid; you deduct them over the term of the loan. The Schedule E instructions say the same about points and loan origination fees charged only for the use of money.
- A refinance can release old points. When a loan ends, including by refinancing, you may be able to deduct the remaining points from the old loan that year. If the refinancing is with the same lender, they generally aren't deductible that year but may be deductible over the term of the new loan.
- Cash-out money follows its use. When you refinance a rental for more than the previous balance, the interest and points allocable to proceeds not related to rental use generally can't be deducted as a rental expense.
- Some loan costs go into basis. Certain expenses to obtain a mortgage on a rental, such as mortgage commissions, abstract fees and recording fees, can't be deducted as interest; Pub 527 calls them capital expenses that are part of your basis.
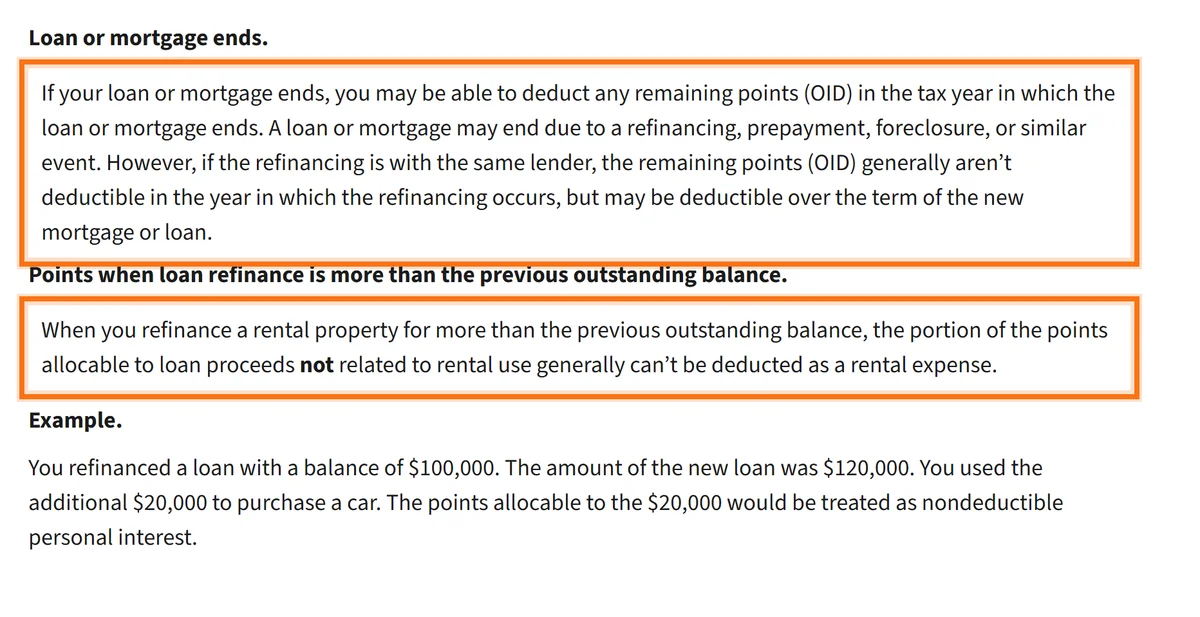
The Schedule E instructions add a practical rule for cash-out money: interest is allocated the same way the loan proceeds are used, and the easiest way to trace them is to keep the proceeds of a loan separate from any other funds. This is general information, not tax advice; your CPA applies it to your loan.
After closing: what has to be updated
The servicer may change, which changes where the payment and escrow go and who sends the year-end interest statement. Pub 527 says that if you paid $600 or more of mortgage interest on the rental to any one person, you should receive a Form 1098, so a refinance year can bring one from the old lender and one from the new. The insurance policy needs the new lender listed. If a co-owner came off the loan, check whether they also came off the deed, because the lease and the management agreement should match the owner of record.
Revisit the reserve if the payment changed. Nothing about the lease changes because of a refinance.
When refinancing a rental is the wrong move
It is the wrong move when the payback period is longer than you will keep the loan, when a cash-out pushes the house below break-even with no plan to cover it, when a major system is about to fail, or when the cash is not going into an investment. A vacancy or a tenant dispute is usually the wrong time too, because the file is weaker.
It can be the right move when the loan no longer fits how you use the house, when the rate difference is large and you will hold for years, or when equity can fund a property that improves the whole portfolio. Who helps build that strategy? A lender for the loan, a CPA for the tax side, a manager for the rent, condition and records. This is general information, not financial, legal or tax advice.
How Perpetual handles this
Perpetual Property Management is broker-owned, with our office at 5755 Rufe Snow Dr in North Richland Hills, and we manage homes in Keller, North Richland Hills, Fort Worth and nearby. We are not a lender and do not arrange loans. What our site states that a refinance can use:
- Monthly statements in the owner portal, with income, expenses, invoices and documents in one place, plus your disbursement history.
- Your lease documents: you receive a copy of everything through the owner portal.
- Per-property reporting for owners of several homes, which our rent collection page describes as the numbers you need when deciding what to keep, refinance or sell.
- A free rental analysis that sets out a recommended rent range from leased comparables, with the reasoning.
- Renewal work starting 120 days before the lease ends, so you know early whether a fresh lease or a vacancy is coming.
If a refinance is meant to fund another purchase, our affiliated brokerage, Perpetual Realty Group, helps investors buy and sell. What our site does not state, such as whether we meet the appraiser at the home or provide a signed rent letter for a lender, is confirmed in writing before you sign. To talk it through, call 682-593-7033.
The takeaway: Treat a rental refinance as a paperwork exercise and a cash-flow test: get the lender's terms in writing, time it mid-lease with a paying tenant, and check the payment against what the house actually nets.
Questions owners ask
Is it harder to refinance a rental property than a primary residence?
Usually it involves more paperwork, because the lender looks at the property as well as at you: the lease, proof the rent is paid, the insurance and often your tax returns. Each lender sets its own terms for investment property, so ask for the rate, fees, reserve rules and how rental income counts in writing. Owners with clean monthly statements have most of the file already.
Do I need my tenant's permission to refinance?
No. The refinance is between you and the lender. You do need access for the appraiser, which is set by the access clause in your lease; Texas has no statute that sets an entry notice period. Tell the tenant in writing ahead of time, offer a window, and let them know nothing about their lease changes.
Can I count rental income when refinancing an investment property?
Often part of it can count, but how much and with what proof is the lender's rule, and it differs by lender and loan type. Expect to show the signed lease, proof the rent has been paid and, if you have owned the home through a tax year, the return with Schedule E. Ask early, in writing.
When is the right time to refinance a rental?
Mid-lease with a tenant who pays on time, so the lease has term left and the rent record is clean. Avoid applying during a vacancy or in the last weeks of a lease. If a renewal is coming, settle it first so the lender sees a fresh lease. Then set the new payment date to fall after rent arrives.
Does a cash-out refinance on a rental make sense?
It can, if the cash goes into something that earns more than the added payment costs and the rental still pays for itself afterward. Under IRS Publication 527, interest and points on the part of the loan not used for the rental generally can't be deducted as a rental expense, so keep the proceeds separate and track their use.
Can you refinance a rent-to-own property?
Be careful. Under Texas Property Code 5.062(a)(2), an option to purchase combined with a residential lease can be treated as an executory contract, and 5.085 then requires the seller to keep title free from liens for the life of the contract, with narrow exceptions. A refinance adds a lien, so get a real estate attorney's advice before applying. This is general information, not legal advice.
Are refinancing costs on a rental property tax deductible?
Some are, over time. IRS Publication 527 says points are generally deducted over the life of the loan, remaining points on the old loan may be deductible when it ends in a refinancing (generally not with the same lender), and certain costs such as recording fees go into the property's basis. Your CPA applies the rules to your closing statement. This is general information, not tax advice.
Related services
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →