Key takeaways
- Compare like with like: the cash a sale puts in your account against the cash a year of renting leaves after every cost.
- In the illustrative example below, selling leaves $126,000; renting runs minus $2,300 in year one and plus $1,050 in year two, with the equity left in the house.
- IRS Publication 523: the home sale exclusion requires owning the home and living in it for at least 24 months of the 5 years before the sale, so renting starts a clock.
- A rental is taxed without the homestead exemption, which in the Tax Code is for a home occupied as the owner's principal residence.
- Our rent or sell page asks three questions: would the rent cover the mortgage, taxes and insurance, do you need the equity in cash, and what is your mortgage rate?
Should you sell or rent your house? Fill in two numbers and compare them: the cash a sale would leave after selling costs and the payoff, and the cash a year of renting would leave after the mortgage, property tax without the homestead exemption, landlord insurance, fees and repairs. For a house in Fort Worth, Keller or North Richland Hills, the rent line comes from leased comparables, and the tax timing comes from IRS Publication 523.
Below: the fill-in table with an illustrative example, where each number comes from, the IRS rules as the publications state them, the signals that point one way or the other, and the other ways out of a house that is not selling.
The fill-in table: what a sale leaves vs what a year of renting leaves
Here is the table to fill in with your own figures, with an illustrative example (a $400,000 house with a $250,000 payoff that would rent for $2,500 a month; every number is illustrative only, not a quote):
| Line | Where your number comes from | Illustrative example |
|---|---|---|
| A. Realistic sale price | A listing agent's price opinion or recent sales of homes like yours | $400,000 |
| B. Selling costs | Your agent's estimated net sheet: commission, title, repairs, prep | $24,000 |
| C. Mortgage payoff | A payoff statement from your servicer | $250,000 |
| D. Cash from selling (A minus B minus C) | Before any tax on the gain (see the IRS section below) | $126,000 |
| E. Rent received in year one | A rental analysis range, less the month or so it takes to lease | $27,500 (11 months at $2,500) |
| F. Principal and interest | Your mortgage statement | $15,000 |
| G. Property tax as a rental | Your tax statement, without the homestead exemption | $6,000 |
| H. Landlord insurance | A quote for a landlord (dwelling) policy | $2,400 |
| I. HOA dues | Your association statement | $600 |
| J. Management and leasing fees | A written management quote | $4,000 ($2,750 + $1,250) |
| K. Repairs and make-ready | Your own repair history and the rental analysis's make-ready notes | $1,800 |
| L. Year-one cash flow (E minus F to K) | Year two drops the leasing fee and adds a renewal fee | minus $2,300 |
How to read this table: line D is cash you would hold after the sale, before any tax on the gain. Line L is what renting adds to or takes from your bank account in the first year while the $126,000 stays in the house and the tenant's rent pays down the loan. Year one carries the leasing fee and the first vacancy, so judge renting on year two as well.
In the example, year two looks different: 12 months of rent ($30,000), the management fee on 12 months ($3,000), a renewal fee instead of a leasing fee (illustrative $150), and the same mortgage, tax, insurance, HOA and repairs. Costs come to $28,950, so year two leaves plus $1,050. Over the two years the house costs you $1,250 in cash flow while it keeps the equity working and the loan shrinking. Whether that trade is worth it is the decision.
Lines A to D: what selling nets, and whether you need the cash
Start with the number a sale puts in your account, not the list price. Line A should come from an agent's price opinion or recent sales of homes like yours, line B from the agent's estimated net sheet (commission, title charges, repairs a buyer's inspection is likely to ask for, preparing the house), and line C from a payoff statement your servicer issues. In the example, $400,000 less $24,000 less $250,000 leaves $126,000.
Then ask the question that decides more of these choices than the arithmetic: do you need that cash for the next thing? If line D is the down payment on the house you are moving to, renting only works if you can carry both homes. Ask your lender how it will treat the old house's mortgage and rent before you decide; this guide does not guess at a lender's rules.
If you do not need the cash, it stays in a house that a tenant's rent helps pay down. The question then becomes whether that equity earns enough as a rental, which is what lines E to L measure.
Lines E to L: a year of renting after every cost
Rent minus the mortgage payment is not cash flow. The honest version subtracts every cost a rental carries, including the ones that do not show up every month:
- Rent received (E): a range from leased comparables, less the time it takes to lease. The example assumes one month listed before the tenant moves in. That month is rent not received, not a bill you pay.
- Principal and interest (F): from your statement. Part of it is principal, which builds your equity, so it is cash out but not a loss.
- Property tax (G): recalculated without the homestead exemption. Your appraisal district can tell you what changes; see renting out your home and the Texas homestead exemption.
- Insurance (H) and HOA (I): a landlord policy quote and your association statement.
- Management and leasing (J): from a written quote. The example uses an illustrative 10% of monthly rent on the 11 leased months ($2,750) and a leasing fee of half a month's rent ($1,250). Whether any fee applies to a vacant month is set in the management agreement; our own numbers are on the pricing page.
- Repairs and make-ready (K): your own figure from the house's history.
The line-by-line version of this worksheet, month by month, is in will rent cover the mortgage, taxes, insurance and management.
Your mortgage: the rate and what the loan documents allow
Our rent or sell page puts it plainly: a low rate is an asset. If your fixed rate is well below what a new loan would cost, line F is lower than the same house would carry at today's rates, and a sale hands that advantage away. Our Keller page notes that many Keller landlords are owners who moved for work and kept the house; the accidental landlord guide is written for that owner.
The opposite is also true. A high rate, an adjustable loan or a payment that already eats most of the rent makes line L worse every year, and the equity may work harder elsewhere.
Before you rent, read your deed of trust and note, and ask your servicer whether and when the loan allows the house to be rented. Loan terms differ, so this guide does not state a rule for yours. Switch the homeowner policy to a landlord policy before the tenant moves in, and confirm that with your insurance agent.
Tax points as IRS Publications 523 and 527 state them
Taxes can swing this decision, and they belong to your CPA. What the IRS publications themselves say, as read in November 2026:
- The home sale exclusion. Publication 523 lets you exclude up to $250,000 of gain ($500,000 for a married couple filing jointly) if you meet its Eligibility Test.
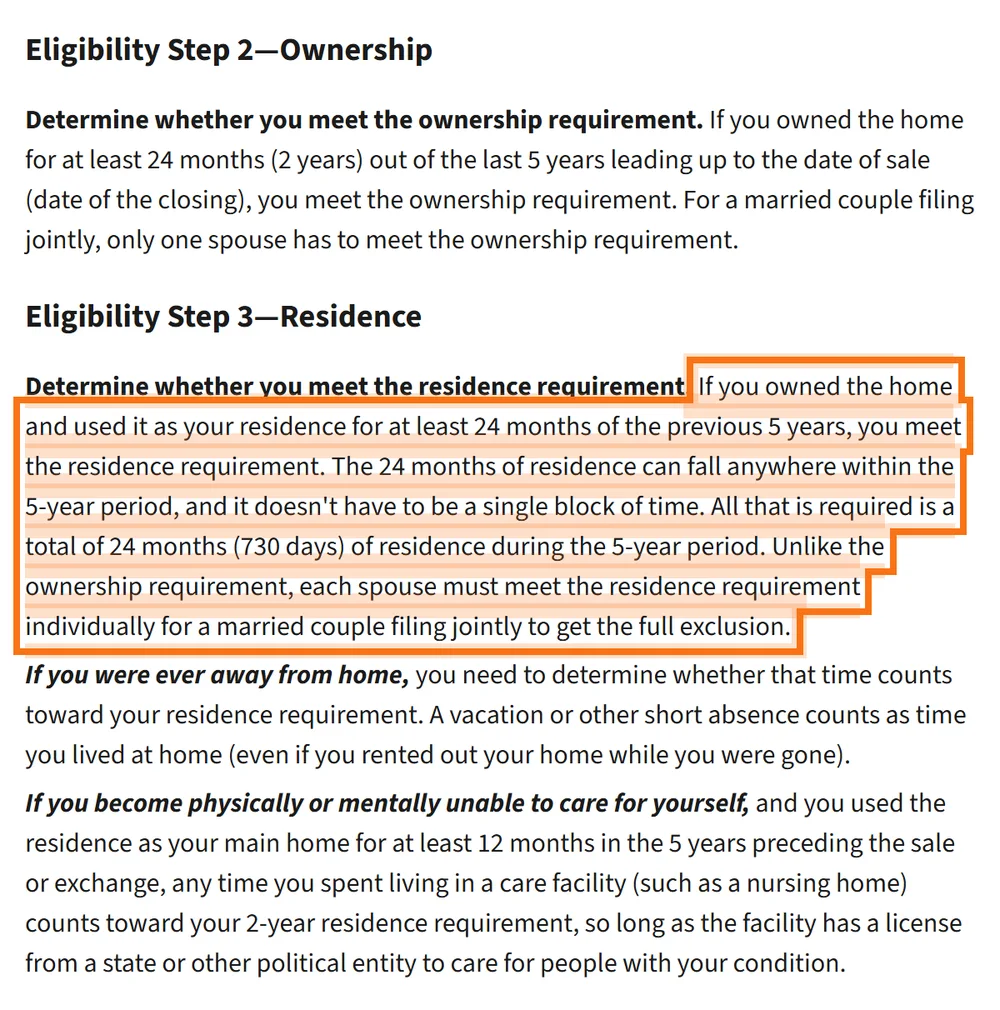
- Ownership and residence. You meet the ownership requirement if you owned the home for at least 24 months out of the last 5 years before the sale, and the residence requirement if you used it as your residence for at least 24 months of the previous 5 years. The 24 months do not have to be a single block.
- Renting after you move out. Publication 523 says a period of nonqualified use does not include the part of the 5-year period after the last date you used the property as your main home.
- Depreciation. You cannot exclude the part of the gain equal to depreciation allowed or allowable after May 6, 1997.
Publication 527 adds two points for the years you rent. When you change your home to rental use, the basis for depreciation is the lesser of its fair market value or its adjusted basis on the date of conversion, and residential rental property is depreciated over 27.5 years under the general system. Those deductions are the depreciation Publication 523 says cannot be excluded at a later sale.
Put together: every month the house is rented moves your 24 months of residence further back inside the 5-year window. Ask your CPA for the last sale date that still passes the test for your dates. Our overview of rental property taxes in Texas explains depreciation in plain terms. This is general information, not tax advice.
Which way the numbers point: the signals
Once the table is filled in, these signals decide most cases:
| Signal | Points toward | How to check it |
|---|---|---|
| You need line D for the next purchase | Selling | Ask your lender how it treats the old house if you keep it |
| Line L is negative in year two as well, with no fix | Selling | Re-run lines E and J with a rental analysis and a written quote |
| Your fixed rate is well below today's loans | Renting | Your note: the rate and whether it is fixed |
| Your IRS 24-month window is closing on a large gain | Selling, or a dated plan | Your move-out date and a CPA |
| The house needs major work to compete as a rental | Selling, unless you will fund it | The make-ready notes in a rental analysis |
| The HOA restricts leasing | Selling, or a longer lease | The declaration and any leasing policy |
| You expect to return or hold for years | Renting | Your own plans, written down |
How to read this table: one signal rarely settles it; three pointing the same way usually do. A low rate and a long hold are the strongest reasons to rent; needing the cash or a closing tax window are the strongest reasons to sell.
Renting also keeps an option open: a rented house can be sold later, with the tenant in place or at the end of the lease, while a sold house is gone. The signals and the arithmetic for selling a house that is already a rental are in when to sell a rental property, and an inherited house has its own steps in rent or sell an inherited house.
If the house is not selling: the other doors
If the house is already on the market and not moving, the choice is wider than sell or rent. Our rent or sell page lays out four doors: lease it through Perpetual Property Management; list it on the MLS yourself through DirectList for a flat fee upfront and a low payment at closing; a creative exit such as owner finance, subject-to or a wraparound, where the mortgage stays in place; or a full-service listing through Perpetual Realty Group. When the home is worth less than the note and there is a provable hardship, the page describes short sale assistance.
Renting as a backup to a stalled sale is covered in house not selling? when renting it out is a sensible backup.
How Perpetual helps with the sell-or-rent decision
Our rent or sell page starts from the same three questions as this guide: would the rent cover the mortgage, taxes and insurance; do you need the equity in cash; and what is your mortgage rate? All four doors on that page are open at Perpetual, and the page says we tell you which one the numbers point to.
What you can ask for:
- A free rental analysis for line E: a rent range from leased comparables, demand notes for your neighborhood, make-ready guidance on which improvements raise rent and which just cost money, and a written management quote for line J. We typically respond within one business day, with an optional 15-minute call.
- A discovery call with Justin Brown, Broker/Owner of Perpetual Realty Group, LLC and Perpetual Property Management: your payoff, your rate and your equity, what the house would rent for and sell for today, and which door fits. No fee and no obligation; bring your mortgage statement. Call 817-228-6817.
The tax side stays with your CPA. To start with the rent line, request the free rental analysis, or call 682-593-7033.
The takeaway: Fill in both columns before deciding: the cash a sale leaves, and the cash a year of renting leaves after every cost. Then add the two things the table cannot show: whether you need the equity now, and how the IRS ownership and residence tests treat the date you would sell. Ask your CPA about the second.
Questions owners ask
Should I sell my Keller house or keep it as a rental?
Fill in both sides: the cash a sale leaves after selling costs and the payoff, and the cash a year of renting leaves after the mortgage, tax without the homestead exemption, insurance, HOA, fees and repairs. Then weigh whether you need the cash, your mortgage rate, and how IRS Publication 523's 24-month residence test treats your sale date. A free rental analysis gives you the Keller rent line.
Can I rent out my house and sell it later?
Yes. A rented house can be sold with the tenant in place or at the end of the lease. Check the IRS timing first: Publication 523 requires that you owned the home and lived in it for at least 24 months of the 5 years before the sale, and depreciation after May 6, 1997 cannot be excluded. Ask your CPA for your dates.
Do I have to pay more property tax if I rent out my house in Texas?
Usually, yes. The homestead exemption in Tax Code 11.13 is for a home occupied as the owner's principal residence, and 11.13(l) keeps it only for a temporary absence of less than two years when you intend to return and have not set up a different principal residence. Ask the appraisal district how your situation is treated, and use the rental figure in your numbers.
Can I rent my house if I still have a mortgage on it?
Often, but your loan documents decide. Read your deed of trust and note, and ask your servicer whether and when the loan allows the house to be rented. Switch to a landlord insurance policy before the tenant moves in. If you are buying another home, ask the new lender how it will treat the old mortgage and the rent.
How long can I rent out my house and still get the home sale exclusion?
IRS Publication 523 requires ownership and residence of at least 24 months each within the 5 years before the sale; the 24 months of residence do not have to be continuous. Every month you rent moves those months further back in the window, so the last qualifying sale date depends on your dates. Ask your CPA to work it out before you sign a long lease.
What does a rental analysis add to a sell-or-rent decision?
It gives you line E from evidence: a rent range from homes that actually leased near yours, demand notes for the neighborhood, the make-ready items worth doing and a written management quote, which fills line J. Ours is free, and we typically respond within one business day.
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →