Key takeaways
- The claim math has three inputs: the estimate, the deductible, and whether the roof is paid at replacement cost or actual cash value.
- OPIC: even with replacement cost coverage, roofs may only be paid at actual cash value, which subtracts depreciation for age and wear.
- A percentage deductible is figured on your dwelling coverage, not on the claim, so a smaller repair can fall entirely under it.
- Insurance Code 707.002: the insured pays the deductible. Business and Commerce Code 27.02: a seller may not waive it without the insurer's consent.
- Insurance Code 4102.163: a contractor may not act as a public adjuster on a property it is or may be working on.
Hail damage to a rental's roof in Fort Worth, Keller or North Richland Hills is first a money question: what the roof will cost to fix, what your deductible is, and whether your policy pays the roof at replacement cost or at actual cash value after depreciation. Those three numbers decide whether a claim pays off, before any roofer knocks on the tenant's door.
Below: the claim math worked three ways, what to know about your roof and policy before storm season, how to choose a roofer under Texas law, and the tenant during the work. The check right after a storm is in can a property manager check my house after a hailstorm, and the claim itself in working with your insurer during a claim.
The claim math: three illustrative hail cases
Here is how the same storm can play out under different policy terms. Assumptions, illustrative only and not a price for any roof: dwelling coverage of $300,000 with a 2% wind/hail deductible ($6,000), a full replacement estimate of $12,000, and $4,000 of depreciation for the roof's age and wear:
| Case | Insurer pays | You pay | How it adds up |
|---|---|---|---|
| Full replacement, roof paid at replacement cost | $6,000, in two parts | $6,000 (the deductible) | First check $12,000 - $4,000 depreciation - $6,000 deductible = $2,000; the $4,000 holdback after the work is done and the deductible is paid |
| Full replacement, roof paid at actual cash value | $2,000 | $10,000 | $12,000 - $4,000 depreciation - $6,000 deductible = $2,000; no second check |
| Partial repair estimated at $3,000 | $0 | $3,000 | The estimate is below the $6,000 deductible |
How to read this table: the same roof and the same storm produce an insurer payment of $6,000, $2,000 or nothing, depending on two lines in your policy. Run the same three rows with your own declarations page and your roofer's written estimate before you decide whether to file. The deductible and depreciation figures here are examples, not typical amounts. This is general information, not insurance advice.
Why hail damage on a roof is hard to judge from the ground
Hail does not always leave damage you can see from the yard, and the first sign on a rental can be a ceiling stain months later. That gap matters twice: the damage inside becomes a second problem on top of the roof, and your policy may set its own deadline and duties for reporting a loss. Read those terms now, not after the stain appears.
The roof is the largest storm item on most rentals, and it is the one where what you know before the storm changes the outcome most. The Office of Public Insurance Counsel advises getting the roof inspected regularly and keeping gutters clear as part of storm preparation.
Before storm season: your roof and your policy
Three things on file before spring make every later decision easier:
- The roof's age, material and last invoice. Age and wear drive depreciation, which is the gap between the two payment methods below.
- Dated photos of the roof from the last inspection, to show its condition before the storm.
- Your policy's roof terms, from the declarations page.
On the policy, OPIC explains that actual cash value is the cost to replace or fix minus depreciation, and replacement cost value is the cost to replace or fix. Even with replacement cost coverage, some property may only be paid at actual cash value, and roofs are on that list:
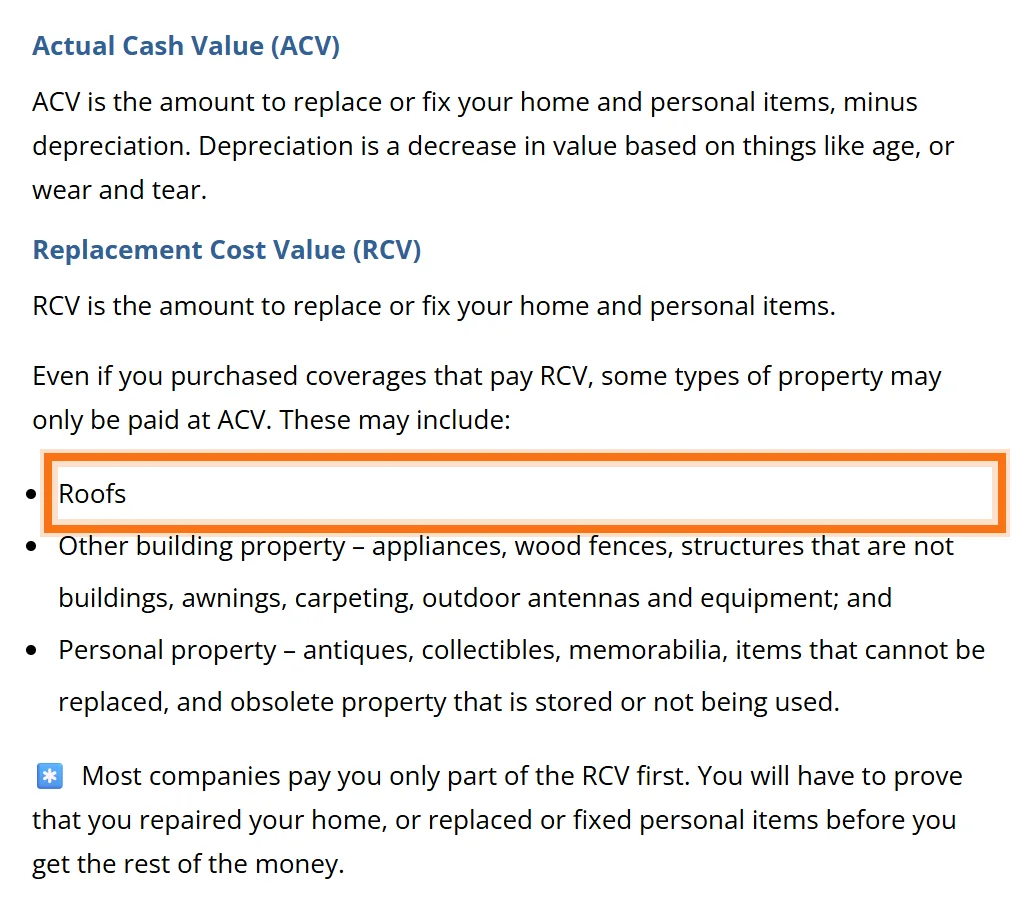
OPIC's spring storm guide adds that roofs or fences damaged by windstorm or hail are often paid at actual cash value. Deductibles are either a flat amount or a percentage of the home's insured value, not of the claim, and a wind/hail deductible can apply to any wind or hail event. Ask your agent which applies to your roof. The landlord insurance guide covers the rest of a rental policy. This is general information, not insurance advice.
The first days after the storm
The first days after a storm are about safety and evidence: contact the tenant, look at the outside and the ceilings, photograph everything with the date, and stop any active leak. That check is covered step by step in the post-storm check on a rental, including where to confirm that hail was reported near the house. Two rules carry over to everything below: do not sign anything a door-knocker offers, and do not decide about a claim until a roofer you chose has looked at the roof itself.
Deciding whether to file
Not every hailstorm is a claim. A filing that comes in under the deductible pays nothing, as the third row of the claim-math table shows. The decision needs an honest inspection first.
Ask a roofer you chose, not one who found you, for a written assessment with photos: which slopes are damaged, whether a repair or a full replacement is needed, and whether vents, gutters and flashing were hit. A roofer who tells you the damage is minor is worth more to you than one who says every roof needs replacing.
Then put the estimate against the deductible and the payment method. File when the damage is real and the numbers work, not because a neighbor did. Ask your agent how a claim may affect your policy before you decide.
Choosing a roofer in Texas after a hailstorm
Within days of a hailstorm, door-knocking crews reach the neighborhood, and the tenant often meets them first. Warning signs: a signature wanted on the first visit, an offer to handle the claim, no local address you can check, or an offer to cover the deductible.
That last one is not a bargain. Insurance Code 707.002 says the insured shall pay any deductible on a first-party property claim. Under Business and Commerce Code 27.02(c), a seller paid from a property insurance claim who pays, waives or absorbs the deductible, or offsets it with a rebate or credit, without the insurer's consent commits an offense, a Class B misdemeanor under 27.02(d). A contract of $1,000 or more expected to be paid from the claim must carry a deductible notice in at least 12-point bold type (27.02(b)).
What to ask for:
- A physical local address and references from earlier work nearby.
- Insurance certificates sent to you or your manager directly.
- A written scope: materials, underlayment, decking replacement terms, flashing, vents and cleanup.
- A written workmanship warranty, separate from the material warranty.
- Lien releases at final payment, and no full payment before the work is done.
How a manager builds and keeps a vendor list is in the vendor bench.
The roofer is not your adjuster
Some contractors offer to "handle the claim." Texas law draws a line here. Under Insurance Code 4102.051, a person may not act as a public insurance adjuster without a license, and under 4102.163 a contractor may not act as a public adjuster, or advertise to adjust claims, for any property on which it is providing or may provide contracting services, even if it holds an adjuster license or a power of attorney.
Your roofer can meet the adjuster, point out damage and submit photos and an estimate. Negotiating the settlement is yours, or a licensed public adjuster's who is not also doing the work. If a roofing contract gives the roofer authority over your claim, ask your agent or an attorney before signing. This is general information, not legal advice.
How the money arrives: depreciation, holdbacks and proof
On a replacement cost policy, OPIC notes that most companies pay only part of the replacement cost first, and you must show the repair was done before you get the rest. Texas Insurance Code 707.004 adds a second condition: an insurer with replacement cost coverage may withhold recoverable depreciation or a replacement cost holdback until it receives reasonable proof that you paid the deductible, such as a canceled check, a money order receipt, a credit card statement or a signed installment plan for the full deductible.
In practice: pay the roofer the deductible in a traceable way, keep the receipt, and send the insurer the final invoice, completion photos and proof of payment promptly. On a roof paid at actual cash value there is no second check, as the claim-math table shows. Adjuster visits, supplements and disputes are covered in the insurance claims guide.
The tenant during the roof work
A roof replacement is a loud, messy day or two. The tenant needs written notice of the date, the hours and what to expect: noise from early morning, debris in the yard, a dumpster or trailer in the driveway, and a nail sweep afterward. Ask them to move cars, keep pets inside and take fragile items off the walls. No Texas statute sets an entry-notice period; the lease's access clause governs.
If water reached the inside, the tenant's belongings are not on your policy; a renters policy covers personal items inside a rented home, as OPIC explains, which is why the lease should require one. See should I require renters insurance. Whether rent changes while a home is partly unusable after a casualty is covered by Property Code 92.054, explained in the post-storm guide. Keep the tenant updated between the storm and the roofing date; weeks can pass.
How Perpetual handles roof and storm work
Perpetual Property Management is broker-owned, with our office in North Richland Hills, managing homes in Keller, North Richland Hills, Fort Worth and nearby. What our site states that applies to roof and storm work:
- Emergencies. Anything threatening the property or habitability, such as an active leak, follows a 24/7 process; 24/7 emergency response is on every plan (maintenance coordination).
- Planned attention to roofs. Much of Northeast Tarrant's housing is 30 to 50 years old, and our maintenance page says planned attention to aging HVAC, water heaters and roofs beats emergency pricing.
- Spending limits. Repairs under your pre-approved limit go ahead; anything larger, such as a roof, comes to you with a description, photos and a recommendation.
- Proof and invoices. Every completed repair over $500 gets photo or video proof in your portal, and the original vendor invoice is always there.
- Before photos. An annual property inspection on every plan, with photo reports.
Whether we meet the adjuster for you and how a claim is coordinated are confirmed in writing before you sign. For a roof question on your rental, call 682-593-7033.
The takeaway: Before storm season, know your roof's age and condition, your wind/hail deductible and whether the roof is paid at replacement cost or actual cash value; after a storm, let those numbers and an honest roofer's estimate decide the claim, and never let a roofer waive the deductible or act as your adjuster.
Questions owners ask
How do I know if my rental's roof has hail damage?
Often you cannot tell from the ground. Look for dents in gutters, vents and the air conditioning condenser, torn window screens and granules at the downspouts, then have a roofer you chose inspect the roof itself and give you a written assessment with photos. The post-storm check is covered in our guide on checking a house after a hailstorm.
Should I file an insurance claim for hail damage on my rental?
Only after an honest inspection shows real damage and the numbers work. Compare the roofer's estimate with your wind/hail deductible, and check whether your policy pays the roof at replacement cost or at actual cash value, which subtracts depreciation. A repair below the deductible pays nothing. Ask your agent how a claim may affect your policy.
Can a roofer waive my deductible in Texas?
No. Insurance Code 707.002 requires the insured to pay any deductible on a first-party property claim. Under Business and Commerce Code 27.02(c), a seller paid from the claim who pays, waives or absorbs the deductible, or offsets it with a rebate or credit, without the insurer's consent commits a Class B misdemeanor. Treat the offer as a reason to choose a different roofer.
Who pays for a tenant's belongings damaged by a roof leak?
Usually the tenant's own renters insurance. OPIC explains that a dwelling policy covers the house and other structures, not personal items, while a renters policy covers personal items inside a rented home. That is why the lease should require renters insurance and the manager should check for it at move-in.
Does the tenant have to let a roofer in after a storm?
The lease's access clause governs; no Texas statute sets an entry-notice period. Most roof work is outside, but the roofer needs the driveway and sometimes the attic. Give the tenant written notice of the date and hours, ask them to move cars and keep pets inside, and keep them updated until the work is finished.
Can a property manager check my house after a hailstorm or severe weather?
Yes. A manager can contact the tenant, check the outside and the ceilings, photograph everything with the date and stop an active leak, then bring in a roofer when the ground check shows damage. The claim decision stays with the owner. Our guide on checking a house after a hailstorm walks through each step.
What is the difference between actual cash value and replacement cost for a roof?
OPIC defines replacement cost value as the cost to replace or fix the property, and actual cash value as that cost minus depreciation for age and wear. Even with replacement cost coverage, OPIC says some property, including roofs, may only be paid at actual cash value. On an older roof the difference can be large, so check your declarations page.
Can my roofer handle the insurance claim for me in Texas?
Not as your adjuster. Insurance Code 4102.163 says a contractor may not act as a public adjuster, or advertise to adjust claims, for a property it is or may be working on, even with a license or a power of attorney. The roofer can show damage and submit an estimate; the settlement is yours or a licensed public adjuster's.
Related services
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →