Key takeaways
- No Texas statute sets a minimum credit score to rent. The number, or whether you use one at all, is your written criteria.
- Property Code 92.3515 requires the selection criteria, including credit history, to be made available when the application is given out.
- A score is a lender's summary. The report behind it, especially money owed to past landlords, tells you more about rent.
- Denying an applicant, or requiring a co-signer or a larger deposit, because of a screening report triggers a federal adverse action notice.
- Apply the same standard to every applicant. Consistency is what makes a credit rule defensible.
What credit score should you require for your rental? There is no legal minimum in Texas: the standard is yours to set, in writing, before anyone applies. On a rental in Fort Worth, Keller or North Richland Hills, a defensible credit rule says what in the report leads to a denial or a condition, is made available with every application, and is applied the same way to everyone. The score is where the review starts, not where it ends.
This guide covers what the law requires and what it leaves to you, what in a credit report predicts rent, how to handle applicants near the line or with no score, and the notices owed when a report changes the answer. How credit fits with income, rental history and the rest of a screening standard is in tenant screening criteria in Texas.
Credit score for renting: what the law requires and what you decide
Here is what is fixed by Texas or federal rules and what is left to your written criteria when credit is part of the decision:
| Question | The rule | Where it comes from |
|---|---|---|
| Is there a minimum credit score to rent? | No statute sets one. The landlord decides whether to use a score and where the line sits. | Your written tenant selection criteria |
| Must applicants see the credit standard? | Yes. Printed notice of the selection criteria and grounds for denial, including credit history, is made available with the application, and the applicant signs an acknowledgment. | Texas Property Code 92.3515 |
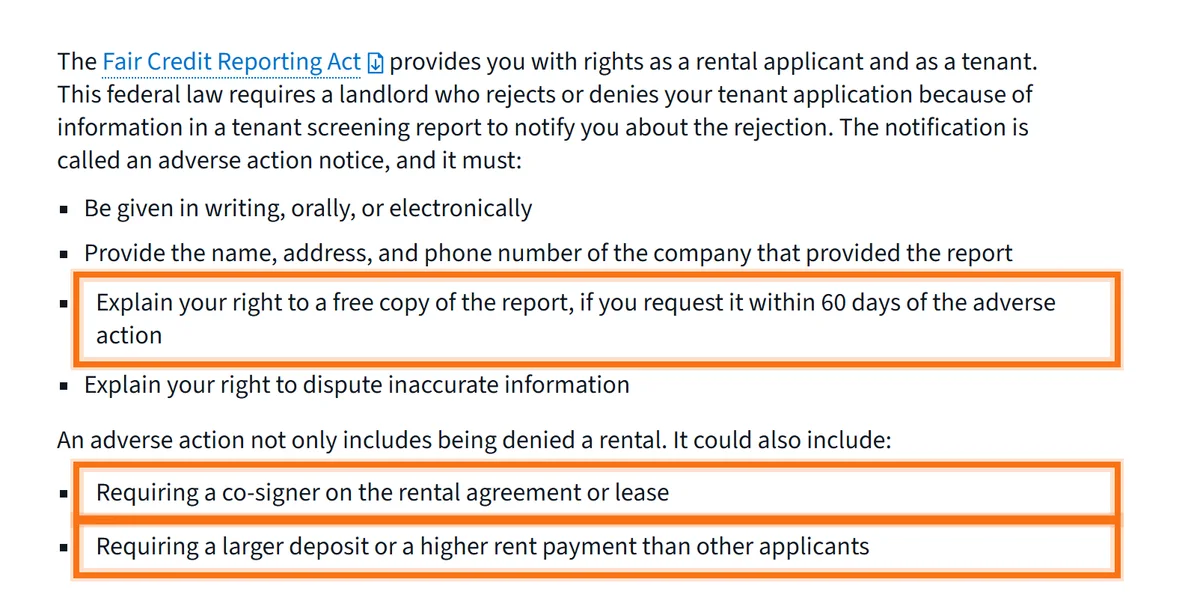
| What if I deny someone because of the report? | An adverse action notice: the screening company's name, address and phone number, the right to a free copy if requested within 60 days, and the right to dispute. | Fair Credit Reporting Act, as the CFPB explains it |
| What if I approve with a condition instead? | Requiring a co-signer, a larger deposit or a higher rent than other applicants can also be an adverse action. | Fair Credit Reporting Act, as the CFPB explains it |
| Can the standard differ between applicants? | No. Whatever you require, require it of everyone in the same situation. | Fair housing law and your written criteria |
How to read this table: the number itself is the only part left entirely to you. Everything around it, telling applicants the standard in advance, explaining a denial or a condition, and applying the rule evenly, is required. An owner who gets those right can choose almost any reasonable credit rule and defend it.
Is there a minimum credit score to rent an apartment or a house?
People search for the credit score needed to rent an apartment as if there were one number. There is not. No Texas statute sets a minimum, and each landlord or manager decides whether to use a score at all and where to draw the line. That is why an applicant can be approved at one house and declined at the next with the same score.
A score compresses years of borrowing into one figure built for lenders. Two applicants with the same number can be very different renters: one has a thin file because they are young and pay cash, the other has a long file pulled down by money owed to a former landlord. The owner sets the standard, informed by the manager's experience, and writes it into the criteria before anyone applies, not after seeing who showed up.
What in the report matters more than the score
A tenant screening report is broader than a credit report. The Consumer Financial Protection Bureau describes it as possibly including credit reports, rental history including eviction actions and lawsuits, employment verification, criminal history, and a risk score or recommendation based on criteria selected by the landlord. Once an applicant clears your credit rule, read the report for housing behavior first:
- Money owed to a previous landlord. Someone already lost money renting to this person. Our own criteria list outstanding debt or unpaid charges to a previous landlord as a cause for rejection.
- Unpaid utility bills. A utility that cannot be put in the tenant's name is a practical problem on day one; our criteria list excessive unpaid utility bills as a cause for rejection.
- Recent late payments, especially a pattern in the last year, which suggests the budget is strained now.
- Bankruptcy. Our criteria list a bankruptcy within the last year that has not been discharged or dismissed.
Old items that have nothing to do with housing, or student loans in good standing, say far less about whether rent will arrive on the first.
Setting the line, a conditional band and a rule for no score
A workable credit rule usually has three parts, all written down. Above the line, credit is a pass and the decision moves to income and rental history. Below a lower floor, credit is a denial. Between the two sits a conditional band, where an otherwise strong applicant can be approved with a stated condition, such as a larger deposit or a guarantor who meets the full criteria. Texas sets no statewide cap on the deposit amount, but a condition required because of the report is an adverse action that needs the federal notice.
The condition must be fixed in advance. If a score in that band means a larger deposit, it means a larger deposit for every applicant in that band. Thin files need their own line too: a young applicant, a newcomer to the country or someone who avoids debt may have no score at all. Decide whether no score is a conditional case, with bank statements and rental history carrying more weight, or a failure. Either answer is defensible if it is written and consistent. The guarantor side is covered in should I accept a co-signer or guarantor.
The adverse action notice, and why the standard must be identical
When the screening report is the reason for a denial or a condition, federal law requires a notice. The CFPB explains that under the Fair Credit Reporting Act the landlord must tell the applicant, and the notice can be given in writing, orally or electronically. It names the company that provided the report and explains the applicant's rights to a free copy and to dispute inaccurate information.
Fair housing law does not tell you what score to require; it requires that whatever you require, you require of everyone. The risk is rarely an owner who sets out to discriminate. It is the one who lowers the bar for one applicant and holds it for the next. Written criteria are the defense, and they also answer the applicant who argues or offers extra cash to get around a rule. The full picture is in fair housing rules for Texas landlords. This is general information, not legal advice.
An example: three applications in one week
Illustrative only. You own a house in North Richland Hills renting for $2,000 a month, and your written criteria set a credit line, a conditional band with a larger deposit and a denial floor. Three applications arrive in one week.
The first applicant is above the line, but the report shows a collection from a former landlord, which your criteria list as a cause for rejection. Denied, with an adverse action notice. The second sits in the conditional band after late card payments during a job change; income is strong and the current landlord confirms on-time rent. Approved with the larger deposit, and because the condition came from the report, the applicant also gets the notice. The third has no score, is new to the country and provides bank statements and an employer letter; the criteria treat a thin file as a conditional case, so it is evaluated on that basis.
None of those outcomes depended on anyone's gut, and each can be explained to the applicant. The full path from application to approval is in how tenant screening works.
What to ask a manager about their credit standard
Before you sign a management agreement, ask four things. What is the written credit standard, and can you see it? Who decides where the line sits for your house, and can you set it higher? How are adverse action notices handled when a report leads to a denial or a condition? And when an applicant is presented, do you see what sat behind the score or only the number?
A manager who answers with documents is running screening that can be checked. A manager who says they look at the whole picture without a written standard is describing a process you cannot verify and an applicant cannot rely on.
How Perpetual handles this
Perpetual Property Management is broker-owned, with our office at 5755 Rufe Snow Dr in North Richland Hills, and we lease homes in Keller, North Richland Hills, Fort Worth and nearby. What our site states about credit and screening:
- Credit is one part of a published standard. Our rental criteria state that every application includes a credit history evaluation, rental history verification, employment and income verification and a criminal background check on all applicants.
- Patterns over a single number. Our tenant screening page puts it this way: patterns matter more than a single score, meaning how an applicant has handled obligations over time.
- Listed causes for rejection, including excessive delinquent credit accounts, excessive unpaid utility bills, outstanding debt to a previous landlord and a bankruptcy within the last year that has not been discharged or dismissed.
- The same criteria for every applicant. All applicants are evaluated against the same written criteria, and we support and comply with the Fair Housing Act.
Our published criteria do not state a minimum credit score. Whether one applies to your house, how a conditional approval is handled and what you see about each applicant are confirmed in writing before you sign. To set the standard before you list, call 682-593-7033 or request a free rental analysis.
The takeaway: Set a written credit rule before you list, read the report rather than stopping at the score, give the federal notice when a report changes the answer, and apply the rule to every applicant.
Questions owners ask
Is it legal in Texas to deny a rental applicant based on credit score?
In general, yes, if credit is part of written criteria applied to every applicant and the decision is not based on a protected characteristic. Property Code 92.3515 requires the criteria, including credit history, to be made available with the application. If the denial is based on a screening report, the federal Fair Credit Reporting Act requires an adverse action notice. This is general information, not legal advice.
Can I require a higher security deposit for an applicant with lower credit?
You can use a larger deposit as a written condition for applicants in a stated band, applied to everyone in that band. Texas sets no statewide cap on the deposit amount, and the deposit rules on deductions and refunds still apply in full. The CFPB notes that requiring a larger deposit or higher rent than other applicants can be an adverse action, so give the notice when the report is the reason.
Which credit score does a property manager actually see?
Often not the score the applicant sees in a consumer app. The CFPB explains that tenant screening reports are different from credit reports and may include a risk score or recommendation based on criteria the landlord selects. That is one more reason to read the items in the report and to name the report provider in your criteria, so the same kind of score is used every time.
What credit score is needed to rent an apartment or a house in Texas?
There is no single answer, because no Texas law sets a minimum. Each landlord or manager sets its own written criteria, and Property Code 92.3515 requires them to be made available with the application. For a specific home, ask for the selection criteria before paying an application fee.
Is there an average or minimum credit score to rent?
Not one that binds anyone. A figure quoted online describes other landlords, not your house. What counts is the written standard for the home you are renting out or applying for. Our own published criteria do not state a minimum score; they list causes for rejection such as excessive delinquent credit accounts.
Can I deny an applicant who has no credit score at all?
You can, if your written criteria say so and you apply that rule to every applicant with no score. The other option is to treat a thin file as a conditional case and give more weight to bank statements, income verification and rental references. Decide which before you list and write it down.
Related services
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →