Key takeaways
- A property manager must use Form 1099-MISC to report the rent paid over to the owner; rents go in box 1, for amounts of $2,000 or more.
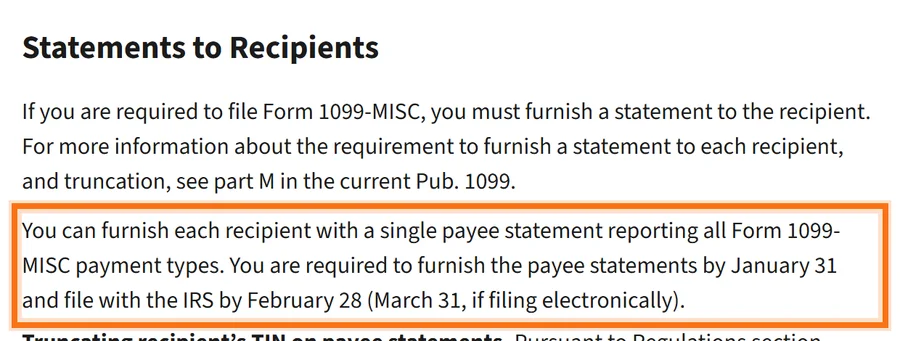
- The IRS instructions require payee statements by January 31.
- Monthly statements and vendor invoices are what turn the 1099 figure into a tax return.
- A deposit you plan to return is not income when received (IRS Publication 527).
- Mortgage interest (Form 1098), property tax and insurance come from others, not the manager.
From your property manager, you should receive a Form 1099-MISC for the rent paid over to you, due to you by January 31, plus the monthly statements, the invoices behind each repair and a record of the security deposit. Your lender, insurer and the tax office supply the documents the manager never touches. That holds for a managed rental in Fort Worth, Keller or North Richland Hills.
This guide is the checklist: each document, who issues it, and what your CPA does with it. How each item lands on Schedule E is in year-end reporting for rental owners.
The year-end documents for a rental, and who issues each
Here is the year-end stack for one managed rental, who issues each piece, and what your CPA does with it:
| Document | Who issues it | What the CPA uses it for |
|---|---|---|
| Form 1099-MISC, box 1 (rents) | Your property manager, for the rent paid over to you; amounts of $2,000 or more | A cross-check of reported rent income against your statements |
| Twelve monthly owner statements | Your property manager | Rent received, management fees, repairs and other expenses, month by month |
| Annual or year-end summary | Your property manager, if the agreement provides one | Totals by category for each property, so the return is not built from twelve pages |
| Vendor invoices | The vendors, kept by the manager | Deciding whether a cost is a repair deducted now or an improvement depreciated over time |
| Security deposit record | Your property manager (or you, if you hold the deposit) | A deposit you plan to return is not income; any part kept is income that year (Publication 527) |
| Form 1098 | Your lender, if you paid $600 or more of mortgage interest | Mortgage interest for Schedule E |
| Property tax statement and receipts | The tax office, or your lender's escrow statement | Property tax expense |
| Insurance declarations and premium notices | Your insurer | Insurance expense |
| Closing statement and improvement records | You (title company, contractors) | Basis and depreciation, which run for years |
How to read this table: the first five rows come from your manager and cover only money that passed through the manager. The last four come from you, your lender, your insurer and the tax office, and include some of the largest deductions. Your CPA needs both halves. This is general information, not tax advice.
The statements: twelve months, and a year-end summary
The monthly owner statements are the backbone. Each one should show rent received, the management fee, repairs and other expenses, reserve movements and the payout to you. A year-end summary rolls the twelve into totals by category, and if you own several rentals, by property, because the Schedule E instructions say to use a separate column for each rental property.
If the monthly statements were complete, the year-end summary is just arithmetic. If they were vague, year-end is when the gaps surface. Whether your manager issues an annual summary, and in what format, is a term to confirm in the agreement before you sign. How to read a single statement is in how to read your monthly owner statement.
Form 1099-MISC for rents: box 1 and the January 31 date
The IRS Instructions for Forms 1099-MISC and 1099-NEC (revised December 2026) list payments of rent to real estate agents or property managers among the payments that do not have to be reported on Form 1099-MISC, and then add: "However, the real estate agent or property manager must use Form 1099-MISC to report the rent paid over to the property owner." Rents go in box 1, which covers amounts of $2,000 or more; for tax years beginning after 2025, the reporting threshold is $2,000.
The figure on the form may not match the deposits that reached your bank, because fees and repairs paid out of the rent appear on your statements as expenses. Ask your manager what the box 1 amount includes, then reconcile it with the year's statements. The form is issued to the taxpayer identification number you gave the manager, so make sure it matches how you hold the property, personally or through an entity.
The invoices and the deposit record
Your CPA may not want every invoice, but you should be able to produce them. IRS Publication 527 says to separate the costs of repairs and improvements and keep accurate records, because a repair is deducted while an improvement is depreciated. A water heater repair and a new water heater land in different places on the return, and the invoice description is what tells them apart.
The deposit record matters for a different reason. Publication 527 says not to include a security deposit in income when you receive it if you plan to return it at the end of the lease; if you keep part of it because the tenant did not live up to the lease, the amount kept is income that year. An amount called a deposit that is really the final month's rent is advance rent, income when received. This is general information, not tax advice.
What still comes from somewhere else
The manager reports only what passed through the manager. Several of the largest deductions never do:
- Mortgage interest. Publication 527 says that if you paid $600 or more of mortgage interest on your rental to any one person, you should receive a Form 1098 or similar statement.
- Property taxes, from the tax statement and your payment or escrow records.
- Insurance premiums, from your insurer.
- HOA dues you pay directly.
- Travel and owner-level costs you track yourself.
- Depreciation, which your CPA calculates from your purchase records and prior returns.
Keep these in the same folder as the manager's package. Rental property taxes in Texas explains the main deductions, and depreciation for rental owners covers the part that confuses most first-year owners.
When it arrives, and handing it to your CPA
The IRS instructions say the payee statements are due to recipients by January 31, and the filer sends the IRS copy by February 28 (March 31 if filing electronically). If your copy has not arrived in the first days of February, ask; a missing form delays your return.
The simplest handover is portal access or one shared folder: the twelve statements, the year-end summary, the invoices, the deposit record and the 1099. If you changed managers during the year, each company reports the rent it paid over to you, so expect statements and a form from each, and give your CPA both sets.
One related form: if your manager pays vendors from your funds, the IRS instructions under "Payments made on behalf of another person" say the payor for reporting purposes is the one who performs management or oversight functions in connection with the payment. Ask your manager and your CPA who files Form 1099-NEC for vendors paid $2,000 or more. This is general information, not tax advice.
Three checks before it goes to the CPA
Spend ten minutes before forwarding anything. First, compare the 1099-MISC box 1 figure with the rent on your statements and make sure you understand any difference. Second, scan the expense lines for anything you do not recognize, or an improvement filed as a repair. Third, total the management fees and check them against the fee schedule in your agreement.
Illustrative only, not a quote: if rent is $2,000 a month for twelve months and the agreement's management fee is 9% of monthly rent, the year's management fee is $180 x 12 = $2,160. Re-added: $2,000 x 9% = $180, and twelve months of $180 = $2,160. If the statements total something else, find the month that differs before your CPA does.
Catching an error now is cheap; catching it after the return is filed means an amended return. This is general information, not tax advice.
Year-end questions to ask before you sign a management agreement
Year-end goes smoothly when the answers are in writing before the first rent is collected. Ask any manager, including us:
- Is there a year-end summary, and does it break income and expenses out by property and by category?
- What does the 1099-MISC box 1 figure include, and how will I reconcile it with my statements?
- Who holds the security deposit, and where will I see it on my statements?
- Who files Form 1099-NEC for vendors paid from my funds?
- Can my CPA get direct access to statements and invoices, or only files I forward?
- If I leave mid-year, what final statement and records do I receive, and when?
Good answers are specific and match the agreement. If the answer to the 1099 question is vague in March, it will be vague next January too. Comparing several managers on questions like these is covered in can I see a sample owner statement before signing up.
How Perpetual handles year-end reporting
Perpetual Property Management is broker-owned, with Justin Brown as Broker/Owner, at 5755 Rufe Snow Dr in North Richland Hills. What our site states about year-end:
- Owner Portal: your statements, documents and disbursement history in one secure AppFolio portal (Owner Portal).
- Tax time: our rent collection page says "your CPA gets a clean year-end package," and that statements and year-end reporting export cleanly from the portal, with access or documents shared with your CPA directly (rent collection and accounting).
- Invoices: the original vendor invoice is always in your portal.
- Several rentals: per-property reporting shows each door separately.
- Payouts: rent we collect is disbursed by the 10th of each month, or that month's management fee is waived, subject to the Guarantee Addendum.
What the year-end package contains for your property is confirmed in writing in your management agreement. Questions about a line on your statement: call 682-593-7033.
The takeaway: By early February you should hold the manager's 1099-MISC, twelve statements, the invoices and the deposit record, plus your Form 1098, tax and insurance papers; check that they agree before they go to the CPA.
Questions owners ask
Why doesn't my 1099 from the property manager match what reached my bank?
The IRS instructions say the manager reports "the rent paid over to the property owner" on Form 1099-MISC, box 1. The money that reached your bank may be lower because management fees, repairs and reserve top-ups came out of the rent first. Those appear on your statements as expenses. Ask your manager what the box 1 figure includes and reconcile it with the statements. This is general information, not tax advice.
Do I get a 1099 if I only own one rental?
Generally yes, if the rent paid over to you reached the reporting amount. The IRS instructions put rents in box 1 for amounts of $2,000 or more, and the $2,000 threshold applies to tax years beginning after 2025. The number of properties does not matter; the form goes to the taxpayer identification number on your agreement. Confirm specifics with your CPA.
Does the property manager send 1099s to the repair vendors?
Ask. The IRS instructions say that when a payment is made on behalf of another person who is the source of the funds, the payor for reporting purposes is the one who performs management or oversight functions in connection with the payment. Which party files Form 1099-NEC for vendors paid $2,000 or more should be settled between you, your manager and your CPA, in writing.
What records should I keep myself for a rental property?
Purchase documents and the closing statement, records of improvements with dates and costs, Form 1098 and other mortgage statements, property tax bills, insurance policies and premiums, HOA dues, expenses you paid directly, and prior-year returns, because depreciation runs across many years. Keep them next to the manager's year-end package.
When should my property manager send the 1099?
The IRS Instructions for Forms 1099-MISC and 1099-NEC say payee statements must be furnished by January 31, with the IRS copy filed by February 28, or March 31 if filed electronically. If your copy has not arrived by early February, ask your manager for it before you meet your CPA.
Is the tenant's security deposit part of my rental income?
IRS Publication 527 says not to include a security deposit in income when you receive it if you plan to return it at the end of the lease. If you keep part of it because the tenant did not meet the lease terms, that amount is income in the year you keep it. A deposit to be used as the final month's rent is advance rent, income when received.
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →