Key takeaways
- Run every rental dollar through one account used only for the property, so the bank statement is a complete record.
- Use the IRS list of rental expenses as your categories, and report each property in its own Schedule E column.
- Repairs are deducted; improvements are capitalized and depreciated. Fixing a broken lock is a repair; replacing an entire HVAC system is an improvement.
- IRS: keep property records until the period of limitations expires for the year you sell the property.
- With a manager, the monthly statement is most of your ledger. You add what the manager does not pay, such as mortgage interest.
What are the basics of rental property bookkeeping? One account used only for the rental, a short list of categories that match the IRS rental expense list, a document behind every number, and a monthly check that the statement matches the bank. Owners in Fort Worth, Keller and North Richland Hills who set this up once stop rebuilding the year from memory every January.
This guide covers the account, the categories, repairs versus improvements, which records to keep and for how long, how a manager's statement fits in, the mistakes that cost money, and the package your CPA needs.
The bookkeeping categories, matched to the IRS rental list
Here are the categories most single-family rentals need, taken from the common rental expenses listed in IRS Publication 527 and the Schedule E instructions, with what goes in each and the rule to know:
| Category | What goes in it | The IRS rule to know |
|---|---|---|
| Rent received | All rent for the property, including advance rent | A deposit you plan to return is not income; any part you keep becomes income that year |
| Advertising | Listing and marketing costs | Deductible rental expense |
| Auto and travel | Trips to the property, with a mileage log | For 2025, the standard rate is 70 cents a mile |
| Cleaning and maintenance | Cleaning, lawn, routine upkeep | Deductible rental expense |
| Insurance | The policy on the rental | A premium paid for more than one year is deducted year by year |
| Legal and professional fees | Tax preparation for the rental, legal fees | Fees to defend title or improve the property are capitalized |
| Management fees | Monthly, leasing and renewal fees | Deductible rental expense |
| Mortgage interest | Interest only, from the lender's statement | Principal is not deductible; points are spread over the loan |
| Repairs | Work that keeps the house in efficient operating condition | Fixing a broken lock, painting a room |
| Taxes and utilities | Property tax, utilities you pay | Deductible rental expense |
| Improvements (not an expense) | Work that betters, restores or adapts the house | Capitalized and depreciated; replacing an entire HVAC system is an example |
How to read this table: the first ten rows are lines you add up for the year; the last row is a list you keep for as long as you own the house, because it is depreciated over years and affects your gain when you sell. Each property gets its own set, since Schedule E uses a separate column for each rental property. This is general information, not tax advice.
One bank account, used only for the rental
Open a checking account for the rental and run every dollar through it: rent in; mortgage, insurance, taxes, repairs and management fees out. Nothing personal touches it, and no rental expense goes on a personal card. That one rule does more than any software, because the bank statement becomes a complete record of the property's year.
Keep the account in the name of whoever owns the house. If an LLC owns it, that means the LLC; the LLC overview covers the setup. With more than one rental, one account can work if every transaction is tagged to a property, but separate accounts are cleaner and make a later sale simpler.
A separate savings account for the reserve keeps that money visible and harder to spend by accident. How much to hold is in how much reserve per rental.
Why the categories should match the tax form
Rental income and expenses go on Schedule E, and its instructions say to use a separate column (A, B or C) for each rental property and to enter the expenses for each property in its own column. If your categories match the IRS list from the first day, the year-end handoff is a sum, not a translation.
Resist inventing categories. A dozen lines that match the form beat forty that feel precise. Two lines need extra care: mortgage interest, because only the interest counts, and improvements, because they are not an expense at all. Owners of several homes will find the per-property side in can a property manager track each rental separately.
Repairs and improvements are not the same line
The line that trips up most owners is between a repair and an improvement. The Schedule E instructions put it plainly: repairs and maintenance keep the property in an ordinarily efficient operating condition, and are deductible; examples are fixing a broken lock or painting a room. Improvements better or restore the property or adapt it to a new use, and must generally be capitalized and depreciated; examples are adding substantial insulation or replacing an entire HVAC system.
Publication 527's own table of improvement examples includes a new roof, a water heater, flooring and wall-to-wall carpeting, and it says to separate the costs of repairs and improvements and keep accurate records. Your bookkeeping job is not to decide the tax treatment. It is to flag every large or whole-system invoice as a possible improvement and attach the invoice, so your CPA can decide.
Records: what to keep, where and for how long
Every number needs a document behind it: an invoice, a receipt, a closing statement, a bank record. Keep them digitally, in one folder per property per year, named with the date, the vendor and the amount. Photograph paper receipts the day you get them.
How long? The IRS says that, generally, you keep records supporting your return until the period of limitations for that return runs out, which is 3 years in the ordinary case, longer in the situations it lists. Records connected to the property itself are kept longer:
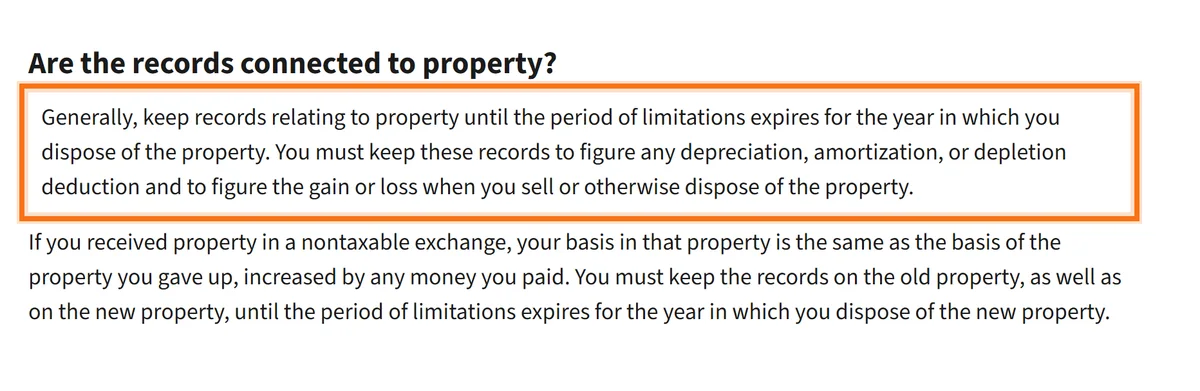
In practice, that means the purchase closing statement and every improvement invoice stay for as long as you own the house and for years after you sell. The improvement invoice from your third year is what supports your basis when you sell in year fifteen. This is general information, not tax advice.
With a manager, the statement is most of your ledger
When a property manager collects the rent and pays the bills, the monthly owner statement is a ready-made ledger: rent collected, each expense with its invoice, the management fee and the amount paid to you. Your job shrinks to checking it. How to read your owner statement walks through each line.
Then record what the manager never sees: your mortgage interest, the insurance premium if you pay it directly, property tax if you pay it, and anything you bought for the house yourself. The statement plus those items is the full picture.
The year-end form from a manager is the 1099-MISC. The IRS instructions for that form say a property manager must use it to report the rent paid over to the property owner. It reports rent paid to you, so your statements, not the 1099, carry the expense detail. Year-end reporting for rental owners covers the forms.
A monthly routine that takes twenty minutes
Put it on the calendar for the same day each month, after the statement arrives:
- Match the manager's payout, or the rent deposit if you self-manage, to the bank statement.
- Open each expense line and confirm the invoice is there. Open any you do not recognize.
- Record the expenses paid outside the manager: mortgage, insurance, taxes, your own purchases and mileage.
- Tag anything large or whole-system as a possible improvement.
- Check the reserve balance against your target.
- Write down anything odd, such as a partial rent payment or an unfamiliar vendor, and ask that week.
A spreadsheet with one tab per property and the categories above as columns is enough for one to three rentals. The test for any tool is simple: can you produce, in ten minutes, one page per property showing the year's income and expenses by category? If not, the routine is the problem, not the software.
The mistakes that cost owners at tax time
The same handful of errors show up every January, and each is avoidable:
- Deducting the whole mortgage payment. Only the interest counts; Pub 527 says you can't simply deduct mortgage principal payments. The lender's Form 1098 shows the interest, and you should receive one if you paid $600 or more of mortgage interest to one lender.
- Booking the whole security deposit as income. Under Pub 527, only the part you keep is income, in the year you keep it, unless the deposit is really the last month's rent, which is advance rent.
- Deducting a reserve contribution. Money left with a manager as a reserve is still your money; only what is spent on the house is an expense.
- Missing small purchases. The paint, the filters, the trip to meet a vendor: small, frequent and forgotten unless logged that week.
- Deducting a prepaid multi-year premium at once. Pub 527 says to deduct only the part that applies to each year.
Rental property taxes in Texas covers the wider tax picture. This is general information, not tax advice.
The CPA handoff: what to send in January
A complete package lets your CPA spend time on judgment instead of reconstruction. For each property, send:
- The manager's year-end statement, or your own category summary if you self-manage.
- Form 1098 from the lender, and any 1099 from the manager.
- The property tax statement and proof of payment.
- Insurance premiums paid, with the policy period.
- A list of possible improvements, with invoices and the date each was finished.
- The closing statement if you bought, sold or refinanced during the year.
- Your mileage log, and the prior-year depreciation schedule if this is a new CPA.
Send it as one folder, labeled by property and year. Fees for preparing the rental part of your return are themselves a rental expense: Pub 527 says you can deduct tax return preparation fees paid to prepare Schedule E, Part I. The year-end documents to expect for your accountant covers the rest.
How Perpetual handles this
Perpetual Property Management is broker-owned, with our office at 5755 Rufe Snow Dr in North Richland Hills, and we manage homes in Keller, North Richland Hills, Fort Worth and nearby. What our site states about the records you get:
- Monthly statements in the owner portal, with income, expenses, invoices and documents in one place, plus your disbursement history. The portal runs on AppFolio.
- The original vendor invoice is always in your portal, and every completed repair over $500 gets photo or video proof, which helps your CPA sort a repair from an improvement.
- A year-end package for your CPA at tax time, as our rent collection and accounting page puts it, and per-property reporting for owners of several homes.
- Every fee you pay is listed in your written agreement; if a fee is not in the agreement, you do not pay it.
- Rent we collect is disbursed to you by the 10th of each month, or that month's management fee is waived, subject to the Guarantee Addendum.
We keep the property's records; your CPA handles the tax treatment. What the site does not state, such as which year-end forms we issue when a home is held in an LLC, is confirmed in writing before you sign. Fees are on the pricing page. To see a sample statement, call 682-593-7033.
The takeaway: One account, the IRS categories, a document behind every number and a short monthly check: that is the whole system, and it is the one that actually gets done.
Questions owners ask
Do I need a separate bank account for my rental property?
Yes, in practice. Running every rental dollar through one dedicated account makes the bank statement a complete record of the property's year, keeps personal and rental spending apart, and makes the CPA handoff far simpler. Keep it in the name of whoever owns the house; if an LLC owns it, that is the LLC.
What expenses can I track for a rental property?
Use the common rental expenses IRS Publication 527 lists: advertising, auto and travel, cleaning and maintenance, commissions, insurance, legal and other professional fees, management fees, mortgage interest, repairs, taxes and utilities, among others. Keep improvements in a separate list, because they are depreciated, not deducted. Track each property in its own column, as Schedule E does.
What is the difference between a repair and an improvement for bookkeeping?
The Schedule E instructions say repairs keep the property in an ordinarily efficient operating condition and are deductible, such as fixing a broken lock or painting a room. Improvements better or restore the property or adapt it to a new use and are generally capitalized and depreciated, such as replacing an entire HVAC system. Flag large items; your CPA decides.
How long should I keep receipts for a rental property?
The IRS says to keep records that support your return until the period of limitations for that return runs out, generally 3 years after filing, longer in some cases. Keep records connected to the property, such as the closing statement and improvement invoices, until the period of limitations expires for the year you sell it. This is general information, not tax advice.
Does a property manager do the bookkeeping for my rental?
A manager records everything that runs through its hands, rent, vendor invoices, fees and payouts, and sends monthly statements; ours also provides a year-end package for your CPA. You still record what the manager does not pay, such as mortgage interest, insurance and property tax if you pay them directly, and check the statement each month.
Is a security deposit income for a rental property?
Not when you receive it, if you plan to return it at the end of the lease, according to IRS Publication 527. If you keep part or all of it because the tenant did not live up to the lease, the amount you keep is income in that year. A deposit meant to be used as the final month's rent is advance rent, income when you receive it.
Can I deduct mileage for trips to my rental property?
Ordinary and necessary auto and travel expenses for your rental can be deducted on Schedule E, line 6. For 2025, the Schedule E instructions give a standard mileage rate of 70 cents a mile, with parking and tolls added, or you can use actual expenses. Keep a log of each trip. This is general information, not tax advice.
Related services
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →