Key takeaways
- Ask for a certificate showing each policy, its limits and the carrier before you sign.
- Errors and omissions (E&O) covers professional mistakes. Texas requires at least $1 million per occurrence only from a broker business entity whose designated broker owns less than 10 percent of it (Occupations Code 1101.355).
- Workers' compensation is elective for private employers in Texas (Labor Code 406.002).
- A licensed broker must hold your rent and the tenant's deposit in a trust account (TREC rule 535.146), and TREC can discipline a broker who acts negligently.
- Insurance only helps if the agreement lets it: read the indemnity clause and any cap on the manager's liability.
What insurance should a property management company carry, and who pays when it makes a mistake? Ask for errors and omissions coverage, general liability, coverage for theft of money it holds and workers' compensation if it has employees, and then read the agreement, because its indemnity clause decides whether a manager's error stays with the manager or lands on you. For a manager of a rental in Fort Worth, Keller or North Richland Hills, Texas law requires only some of that.
This guide covers the coverage to ask for, what Texas requires, the clauses that decide who pays and where your own policy does the work. The landlord policy on the house itself is covered in landlord insurance versus homeowners insurance.
Property management insurance: what to ask for and what Texas requires
Here is each protection worth asking a property management company about, what it is for, whether Texas law requires it and what to ask to see:
| Coverage or protection | What it is for | Required in Texas? | What to ask for |
|---|---|---|---|
| Errors and omissions (professional liability) | Financial loss caused by the company's professional mistakes | Only for a broker business entity whose designated broker owns less than 10 percent of it: at least $1 million per occurrence (Occupations Code 1101.355, 1101.453) | The certificate, the per-claim and aggregate limits, the deductible |
| General liability | Injury or property damage claims arising from the company's operations | No requirement in Occupations Code chapter 1101 or the TREC rules | The certificate and limits |
| Crime or fidelity coverage | Theft or misuse of money the company holds for owners and tenants | No insurance requirement; every broker must keep trust money in a trust account (TREC rule 535.146) | Whether employee theft of trust money is covered, and the limit |
| Workers' compensation | Injuries to the company's own employees | Elective for private employers (Labor Code 406.002) | Whether the company carries it |
| Real Estate Recovery Trust Account | A state fund for actual damages caused by a license holder's listed misconduct, after a judgment that cannot be collected | Maintained by TREC (Occupations Code 1101.601); not insurance | Confirm the broker's license is active with TREC |
How to read this table: the third column is the legal floor, and it is low. Only the first row is ever mandatory, and only for some companies, so the fourth column, what you ask to see, matters more than the law.
Errors and omissions: the policy that matters most to an owner
Errors and omissions insurance, also called professional liability or professional indemnity insurance, is the policy that answers for a manager's professional mistakes: a deposit accounting sent late, a lease clause that does not hold up, a notice served the wrong way. For an owner it is the coverage that matters most, because those are the mistakes that turn into your loss.
Texas makes it mandatory in one situation only. Under Occupations Code 1101.355, a business entity applying for a broker license must provide proof of errors and omissions insurance with a minimum annual limit of $1 million for each occurrence if its designated broker owns less than 10 percent of the entity, and section 1101.453 repeats the requirement at renewal. A company whose designated broker owns 10 percent or more is not required to carry it.
So the question to ask is not "are you insured?" but "show me the E&O certificate, the limit per claim and in total, and the deductible." Every policy has a limit, a deductible and exclusions. A manager that does not carry E&O should say so plainly.
What Texas law adds: the license, the trust account and the recovery fund
Insurance is not the only thing standing between you and a manager's mistake. A company that manages rentals for others in Texas works under a real estate broker license, and the license comes with rules:
- Trust money. Under TREC rule 535.146, rent, security deposits and other money a broker holds for others is trust money, held in a designated trust account and never mixed with the broker's own money, with an accounting to each owner at least monthly when there has been activity.
- Discipline for negligence. Occupations Code 1101.652(b) lets the commission suspend or revoke a license if the license holder, while engaged in brokerage, acts negligently or incompetently, fails within a reasonable time to account for or remit money belonging to another person, or commingles that money with its own.
- The recovery fund. TREC maintains a Real Estate Recovery Trust Account for people who suffer actual damages from a license holder's listed misconduct (Occupations Code 1101.601-1101.602). It pays only after a court judgment that cannot be collected, a suit must be brought within two years (1101.605), and payments are capped at $125,000 per transaction and $250,000 per license holder (1101.610).
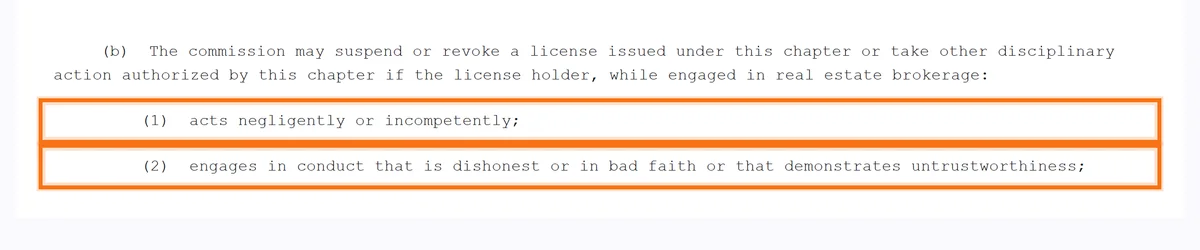
A license complaint can cost a careless broker its license, but it does not repay you. Recovery comes from the company, its insurer or, as a last resort, the recovery fund. How to look up a license is in how to verify a property manager's license in Texas. This is general information, not legal advice.
The indemnity clause: read it before anything else
Nearly every management agreement has a hold harmless or indemnification section, and it usually runs one way: the owner agrees to defend and indemnify the manager against claims arising from the property. That is normal, because the manager acts as your agent and most claims about the house belong to the owner. What you need to check is the carve-out.
A fair clause excludes the manager's own negligence, willful misconduct and breach of the agreement from the owner's indemnity. You cover the manager for ordinary claims about the property, not for the manager's own mistakes. An unfair clause has no carve-out, or one so narrow, such as gross negligence only, that ordinary carelessness is still your problem.
The wording to look for, in plain terms: the owner's indemnity does not extend to losses caused by the manager's negligence, willful misconduct or breach of this agreement. If it is missing, ask for it. The other clauses to read are in the property management agreement: what to look for.
Two common manager errors and who ends up paying
Illustrative scenarios, not real cases. When a mistake does happen, the loss usually reaches you first, because you are the landlord the tenant or vendor can reach; the recovery steps are in what happens if my property manager makes a costly mistake.
A deposit accounting sent late. Property Code 92.109 presumes bad faith when a landlord neither returns the deposit nor sends an itemized list within 30 days after the tenant surrenders the home, and a landlord who keeps a deposit in bad faith owes $100, three times the amount wrongfully withheld and the tenant's attorney's fees. The tenant sues the owner, the landlord of record. If the manager caused the delay, a fair agreement and an E&O policy are what bring that cost back to the manager.
An uninsured vendor. A handyman with no insurance does a roof patch that fails and damages the interior. Your landlord policy may cover the damage, subject to its terms and deductible, and the vendor may have nothing to collect. That is why vendor insurance is checked before work starts. See how a manager checks that contractors are licensed and insured.
Liability caps, limits and what they mean for one house
Two numbers decide whether coverage is real. The first is the policy limit on the manager's E&O and crime coverage. For a company managing many properties, a limit that sounds large is shared by every owner it could owe at once. Ask for the limit per claim and in aggregate, and compare it with the amount of your money that sits in the trust account at the busiest point of the month.
The second is any cap on the manager's liability written into the agreement. Some agreements limit it to the fees paid over a recent period, or to a fixed amount, whatever the loss. That cap can be lower than one month of rent. If there is one, ask for it to be removed or raised to at least the limit of the manager's insurance, so the policy you were shown actually stands behind you. Have a Texas attorney read a cap or a one-sided indemnity before you sign. This is general information, not legal advice.
Where your own coverage still has to do the work
Even with a well-insured manager, your own policies carry the first and largest share of most losses, because you own the property and the risk. The manager's coverage answers only for the slice caused by the manager's own error, after its deductible, and only if the agreement does not push it back to you.
Two practical steps close the gap. Ask your insurer whether the manager can be named as an additional insured on your landlord policy, so a claim at the property does not turn into a dispute between two insurers. And consider requiring renters insurance in the lease, so a tenant-caused loss has a policy behind it; see should you require renters insurance. When a second layer of liability coverage is worth buying is in umbrella insurance for landlords. This is general information, not insurance advice.
What to ask a manager about insurance before signing
- Can I see a current certificate showing your errors and omissions, general liability and crime or fidelity coverage, and do you carry workers' compensation?
- What are the limits per claim and in aggregate, and the deductibles, on the E&O and crime policies?
- Does the agreement's indemnity exclude your own negligence, willful misconduct and breach?
- Is there a cap on your liability in the agreement, and what is it?
- If you make an error that costs me money, what is your process for making me whole?
- What is your license number, and who is the designated broker?
A manager who answers these promptly, with documents, is showing you how it runs the rest of the business.
How Perpetual handles this
Perpetual Property Management is broker-owned, with our office in North Richland Hills, and we manage homes in Keller, North Richland Hills, Fort Worth and nearby. What our site states that bears on liability:
- A Texas broker license. Perpetual Property Management is a DBA of Perpetual Realty Group, LLC (TREC 9008702-BB), and Justin Brown is the broker (TREC 549418-B). Both numbers can be checked on TREC's license search.
- Written guarantees with a stated remedy. The five guarantees of the Perpetual Promise are part of the management agreement, subject to the Guarantee Addendum, and if we miss one, the cost comes out of our fee, not your investment.
- Deposits handled under the Property Code. Deposits are held and accounted for in compliance with the Texas Property Code, with the itemization rules and timelines applied at move-out.
- Insured vendors. If you want your own handyman or vendor, we coordinate with them where they are insured and reliable.
- Every fee in writing. If a fee is not in the management agreement, you do not pay it.
Which insurance policies we carry, their limits and the indemnity and liability terms in our agreement are confirmed in writing before you sign. To review them before you decide anything, contact us or call 682-593-7033.
The takeaway: Ask for the certificate, know that Texas mandates errors and omissions coverage only in one case, and read the indemnity carve-out and any liability cap before you sign, because together they decide who pays for a manager's mistake.
Questions owners ask
What insurance should a property management company carry?
Ask for errors and omissions coverage for professional mistakes, general liability for injury and property damage claims, crime or fidelity coverage for theft of money held in trust, and workers' compensation if the company has employees. Texas requires errors and omissions insurance of at least $1 million per occurrence only from a broker business entity whose designated broker owns less than 10 percent of it. Ask for a certificate showing each policy and its limits before you sign.
What happens if my property manager makes a costly mistake?
The loss usually reaches you first, as the landlord. Raise it in writing with the manager, which may credit or pay a clear error; larger claims go to its errors and omissions carrier. If it denies responsibility, your options are a claim under the agreement, a TREC complaint or a lawsuit, and the indemnity clause and any liability cap decide how far you get.
Does the indemnity clause in a management agreement protect me or the manager?
Usually the manager, because the owner agrees to indemnify the manager against claims arising from the property, which is normal for an agent. What protects you is a carve-out that excludes the manager's own negligence, willful misconduct and breach of the agreement from that indemnity. If the carve-out is missing, you could end up covering the manager for its own mistakes.
Can a property manager limit their liability to the fees I paid?
Some agreements try to, with a cap equal to recent management fees or a fixed amount, and that cap can be lower than a single month of rent. Treat it as binding once you sign. Ask for the cap to be removed or raised to the limit of the manager's errors and omissions coverage.
Should my property manager be named on my landlord insurance policy?
Ask your insurer. Naming the manager as an additional insured on your landlord policy can keep a claim at the property from turning into a dispute between your insurer and the manager's. Your landlord policy still carries the first and largest share of most losses, with the manager's coverage answering only for the slice caused by the manager's own error. This is general information, not insurance advice.
Does Texas require property managers to carry errors and omissions insurance?
Only in one case. Occupations Code 1101.355 requires a business entity seeking a broker license to show errors and omissions insurance with a minimum annual limit of $1 million for each occurrence if its designated broker owns less than 10 percent of the entity, and section 1101.453 repeats that at renewal. An individual broker, or an entity whose designated broker owns 10 percent or more, is not required to carry it, so ask to see the certificate.
Is there a state fund if a property manager mishandles my money?
There is a last resort. The Texas Real Estate Commission maintains a Real Estate Recovery Trust Account for people who suffer actual damages from a license holder's listed misconduct. It pays only after you win a court judgment that cannot be collected, a suit must be brought within two years, and payments are capped at $125,000 per transaction and $250,000 per license holder (Occupations Code 1101.605 and 1101.610).
Related services
Property management in Keller, North Richland Hills and Fort Worth. How full-service management works in Tarrant County →